
The electricity sector is undergoing a regulatory and infrastructure transition. State governments are assuming authority over intrastate electricity markets, renewable-energy programmes are expanding distributed generation, and businesses continue to weigh the cost of grid dependence against investment in alternative power supply. The transition is not yet a substitute for national-grid investment. Its economic value depends on whether new generation projects attract sustainable financing, deliver reliable electricity and reduce the cost of supplying households and productive businesses. Nigeria’s Energy Transition Plan estimates that the additional cost of moving towards net zero will average approximately $10 billion annually over coming decades. Its identified investment pipeline stands at approximately $23 billion, including an estimated $17 billion in private-sector financing needs. These are planning estimates and potential investment opportunities, not evidence that equivalent funds have been mobilized or spent.
Meanwhile, NERC’s transfer of regulatory oversight to Akwa Ibom State in August 2026 brought the reported number of states that had completed the transition to 16. The development expands the geography of subnational electricity regulation, but the commercial results will depend on implementation, investment and service delivery.
Grid Reliability and the Cost of Alternative Power
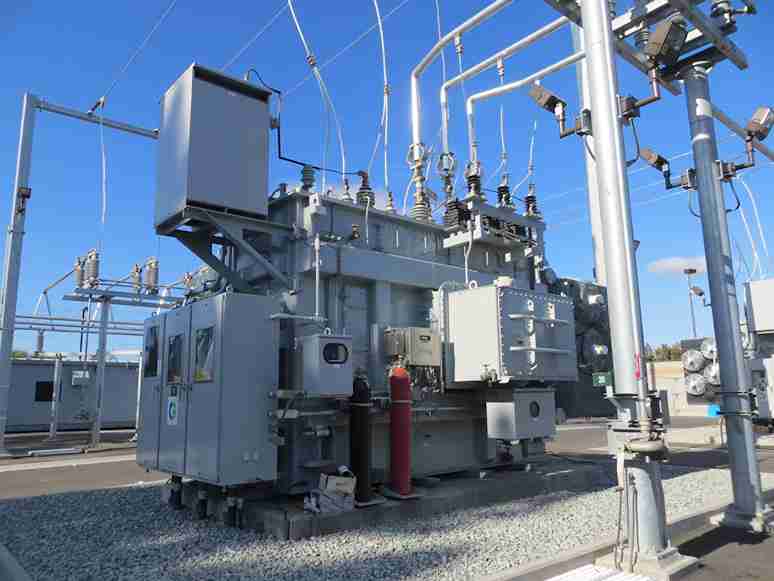
Nigeria’s electricity challenge extends beyond installed generation capacity. The amount of electricity actually delivered depends on available generation, transmission performance, distribution networks, fuel supply and the stability of the interconnected system. On October 19, 2026, reported grid generation fell from approximately 3,840 MW to 476.70 MW following multiple trips on the 330-kilovolt transmission network. The Nigerian Independent System Operator said the incident affected part of the system and did not constitute a nationwide grid collapse. It subsequently reported that restoration measures had returned the grid to normal operation. The episode nevertheless demonstrates how a major supply disturbance can affect businesses and households. Where grid supply is unreliable, firms may incur additional costs for generators, fuel, maintenance, backup systems and production interruptions.
Distributed energy can reduce some of these costs, but its viability varies by application.
- Commercial facilities: Solar and battery systems can reduce daytime grid consumption and improve continuity for selected loads.
- Small businesses and rural enterprises: Mini-grids can support refrigeration, irrigation, retail, digital services and other productive activities where grid access is limited.
- Energy-intensive industry: Continuous-process plants may require larger, dispatchable power sources, extensive storage, grid connections or hybrid systems. A basic solar installation is not automatically sufficient for heavy industrial operations.
The investment decision should compare the full cost of alternative supply with the cost and reliability of available grid electricity. Equipment price alone is an inadequate measure: financing, replacement cycles, fuel, maintenance, system availability and the consequences of downtime all affect the economics. Nigeria therefore needs a complementary power architecture—one that strengthens the national grid while allowing distributed generation to serve loads for which it is technically and commercially appropriate.
“Regulatory devolution creates room for local investment, but a transfer of authority is not the same as an improvement in supply. The test is whether consumers and businesses receive more reliable electricity.”
The Energy Transition Capital Ledger
Nigeria’s Energy Transition Plan sets out a pathway towards net zero by 2060 while seeking to expand energy access and support economic development. Its financing estimates illustrate the scale of the challenge.
| Indicator | Published estimate | Correct interpretation |
| Additional annual transition cost | Approximately $10 billion | Estimated additional cost over coming decades |
| Identified investment opportunity | Approximately $23 billion | Initial pipeline of transition-related projects |
| Private-sector financing requirement within that pipeline | Approximately $17 billion | Estimated funding need, not confirmed disbursement |
| Additional investment above business-as-usual spending, 2021–2060 | Approximately $410 billion | Long-term transition investment estimate |
The figures describe different aspects of the financing requirement and should not be added together as though they were separate pools of money. The $23 billion pipeline is a subset of identified opportunities, while the $410 billion estimate covers additional investment needs across the longer transition period.
The distinction between a funding requirement and capital deployed is central to assessing progress. A pipeline can contain projects at different stages of preparation, including proposals that still require feasibility studies, permits, bankable offtake agreements or credit support. Investors should therefore track the amount of capital committed, the amount disbursed, financial closes achieved and assets commissioned. Without these measures, the size of the announced pipeline says little about the pace at which new electricity supply is becoming operational.
Mini-Grids: Deployment, Access and Industrial Reach
The Nigeria Electrification Programme reports 176 mini-grids deployed across Nigeria and approximately 7.8 million Nigerians impacted. It also reports 94 MW of photovoltaic capacity deployed or installed, alongside programme-reported gains in household and small-business electricity access. These are programme indicators; the number of people reached should not be presented as the number of individual electricity connections.
A further financing initiative was announced on May 14, 2026. The Green Finance and Investment Facility pilot under the Nigeria Distributed Access Through Renewable Energy Scale-up project was launched with $188 million to support 40 planned interconnected mini-grids. The programme announcement identified a combined target capacity of 188.4 MW and approximately 226,000 household and business connections. These are announced deployment targets, not verified completion figures as of October 29. The available announcement does not establish that all 40 projects have been commissioned or that every planned connection is already receiving electricity.
The programme is important because distributed power can support economic activity in underserved communities. However, the scale and type of electricity required vary widely. Mini-grids serving households and small businesses do not necessarily have the capacity to support heavy manufacturing or continuous industrial processes. For developers and investors, the relevant indicators are completed connections, electricity delivered, service reliability, collections, operating costs and the ability of customers to use power productively. For policymakers, the challenge is to expand access without treating connection counts as a complete measure of economic impact.
State Electricity Markets: Sixteen States Have Transitioned
The Electricity Act 2023 provides a framework for states to establish and regulate electricity markets within their jurisdictions, subject to the law’s division of regulatory responsibilities.
NERC reported that 15 states had completed the transfer of intrastate regulatory oversight by May 4, 2026. On August 19, the Commission published an order transferring oversight to the Akwa Ibom State Electricity Regulatory Commission, effective August 18. This brought the reported total to 16 states: The 16 states are Abia, Akwa Ibom, Anambra, Bayelsa, Edo, Ekiti, Enugu, Imo, Kogi, Lagos, Nasarawa, Niger, Ogun, Ondo, Oyo and Plateau.
The transfer is more than an administrative change. State regulators can assume responsibilities for intrastate electricity activities, including relevant licensing, tariffs, consumer complaints and service oversight. Federal jurisdiction remains applicable to matters such as interstate electricity transactions and other functions retained under the Electricity Act. Akwa Ibom’s transfer order also demonstrates that regulatory devolution involves operational work. NERC directed the Port Harcourt Electricity Distribution Company to establish a subsidiary for its intrastate operations, identify relevant network assets and liabilities, and take steps towards the transition. Such arrangements are necessary to separate operations and clarify accountability.
For investors, the opportunity lies in the potential for state-specific generation, distribution and supply arrangements. The risk is that different jurisdictions may develop at different speeds, with varying licensing processes, tariff structures and institutional capacity. The number of states that have completed a transfer is therefore an indicator of regulatory progress, not proof that electricity supply has improved across all 16 markets. That assessment requires evidence of functioning licences, commissioned projects, investment, service quality and effective consumer protection.
“Energy resilience is an industrial cost question as much as an infrastructure question. The objective is dependable power at a cost households and businesses can sustain.”
Financing Costs and Foreign-Exchange Exposure
Electricity infrastructure is capital-intensive, and financing conditions influence which projects proceed. On September 21–22, 2026, the Central Bank of Nigeria reduced the Monetary Policy Rate to 23% from 26.5%, a reduction of 350 basis points. It retained the Cash Reserve Requirement at 45% for deposit money banks, 16% for merchant banks and 75% for non-Treasury Single Account public-sector deposits. The rate reduction has not yet translated into a uniform decline in borrowing costs. CBN Money Market Indicators, as reported by THISDAY, show that the average maximum lending rate rose from 29.20% in August to 32.62% in September 2026.
The maximum lending rate is an average indicator of the upper end of bank lending rates; it is not the rate every borrower pays. Actual project financing depends on borrower risk, collateral, tenor, bank funding costs and contractual terms. Nevertheless, the data demonstrate why a reduction in the policy rate should not be treated as proof that long-term infrastructure finance has become cheaper. Foreign-exchange exposure creates a separate problem. A developer earning revenue in naira may face higher local-currency costs when imported equipment or debt service is denominated in foreign currency. The risk is particularly relevant where tariffs cannot be adjusted quickly enough to absorb depreciation or increases in operating costs.
Developers can mitigate this exposure through suitable currency matching, longer-tenor local-currency financing, guarantees, concessional capital and carefully structured foreign-currency facilities. The appropriate mix depends on project revenues, customers, equipment sourcing and contractual protections. The financing issue is therefore not simply whether capital is available. It is whether funding can be secured at a cost, tenor and currency structure compatible with the project’s expected cash flow.
Industrial Competitiveness and Carbon Border Rules
Nigeria’s electricity transition also intersects with export competitiveness. Manufacturers using carbon-intensive electricity and production processes may face increasing pressure to document the emissions associated with their products, particularly when selling into markets with specific climate-related trade requirements. The European Union’s Carbon Border Adjustment Mechanism entered its definitive phase on January 1, 2026. Its scope covers specified goods, including iron and steel, aluminium, cement, fertilizers, electricity and hydrogen, subject to the applicable rules. It is not a blanket prohibition on high-emission Nigerian exports. The obligations apply through the EU framework to covered imports, and the direct exposure of a Nigerian producer depends on its products, destination market and position in the supply chain.
For affected manufacturers, reliable electricity and emissions measurement can become part of a broader competitiveness strategy. Solar power may reduce emissions associated with electricity consumption, but its contribution depends on the production process and the relevant accounting methodology. Some industries may also require improvements in energy efficiency, process technology, fuels and equipment. Businesses should first determine whether their products fall within the mechanism’s scope, what information their buyers require and how emissions must be calculated or verified. Treating CBAM as an immediate barrier for every Nigerian exporter would overstate its reach; ignoring its requirements for covered goods would understate the risk.
Bold Lite Infrastructure Outlook
Nigeria’s electricity transition is progressing through three connected channels: regulatory decentralization, distributed-energy deployment and efforts to finance a lower-emission energy system. None removes the need to improve national-grid reliability.
Four measures should guide future assessments:
- Capital execution: Track how much of the transition pipeline reaches financial close, disbursement and commissioned operation.
- Service delivery: Measure electricity supplied, reliability, operating costs and the productive use of new connections.
- Regulatory implementation: Assess whether state-market transfers lead to effective licensing, clear tariffs, viable projects and stronger consumer protection.
- Industrial competitiveness: Examine the delivered cost of power, exposure to foreign-exchange movements and emissions requirements for covered exports.
The strategic objective is not decentralization for its own sake. It is a more reliable and financially sustainable electricity system in which the national grid, state markets and distributed generation serve complementary roles.
Editorial conclusion: Nigeria’s power-sector reform will be judged by the electricity it delivers, the cost at which it is supplied and the investment it can sustain—not by the number of regulatory transfers or projects announced.
References
Key Objectives – Nigeria Energy Transition Plan. (n.d.). https://energytransition.gov.ng/objectives/
Finance and Investment – Nigeria Energy Transition Plan. (n.d.).https://www.energytransition.gov.ng/finance-and-investment/
NEP. (n.d.). https://nep.rea.gov.ng/ — reported mini-grid deployments, photovoltaic capacity and programme-reported reach.
Nigeria launches $188 million green Finance facility to drive 40 interconnected Mini-Grids under DARES. (n.d.). https://nep.rea.gov.ng/posts/news-Nigeria-Launches-188-Million-Dolars-Green-Finance-Facility.html
Limited, D. I.-. C. (n.d.). NIGERIAN ELECTRICITY REGULATORY COMMISSION. https://nerc.gov.ng/resources/transfer-order-of-regulatory-oversight-to-akwa-ibom-state-electricity-regulatory-commission-akserc/
Limited, D. I.-. C. (n.d.-b). NIGERIAN ELECTRICITY REGULATORY COMMISSION. https://nerc.gov.ng/
Central Bank of Nigeria. (n.d.). Monetary Policy Decisions | Central Bank of Nigeria. https://www.cbn.gov.ng/MonetaryPolicy/decisions.html
Central Bank of Nigeria. (n.d.-b). Money Market Indicators | Central Bank of Nigeria. https://www.cbn.gov.ng/rates/mnymktind.html
Carbon Border Adjustment Mechanism. (2026, August 3). Taxation and Customs Union. https://taxation-customs.ec.europa.eu/carbon-border-adjustment-mechanism_en
Central Bank of Nigeria. (n.d.-b). Money Market Indicators | Central Bank of Nigeria. https://www.cbn.gov.ng/rates/mnymktind.html