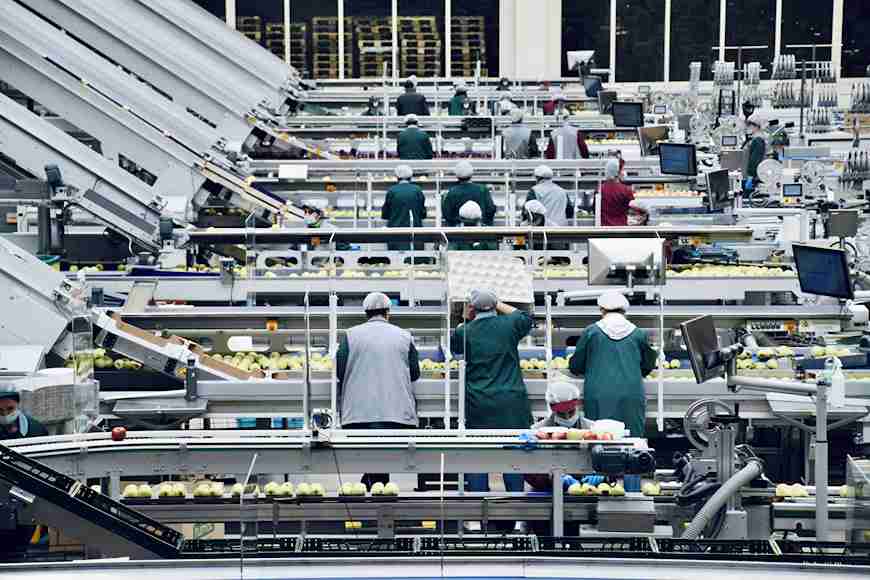

The figures raise questions about the extent to which local sourcing and backward integration are reducing manufacturers’ dependence on imported inputs. Although industry analysts identify these as possible explanations, the aggregate data do not establish how much of the decline resulted from domestic substitution rather than changes in production, purchasing patterns or import timing. Nigeria’s industrial-sector foreign-exchange utilization fell by 21.2% to US$3.72 billion in the first half of 2026, from US$4.72 billion in the corresponding period of 2025. The figures, drawn from the Central Bank of Nigeria’s Q2 2026 Statistical Bulletin and reported by BusinessDay on October 27, show a reduction of approximately US$1 billion in the category. The decline coincided with a sharp increase in foreign-exchange utilization for manufactured products. That category rose to US$2.14 billion from US$1.03 billion, an increase of 107.4%, or US$1.11 billion.
Nigeria’s industrial outlook remains uneven. Manufacturing grew by 3.24% year on year in Q2 2026, while the broader industrial sector expanded by 3.96%, down from 7.46% in Q2 2025. September business-confidence data also showed overall activity strengthening as the manufacturing index moderated. For policymakers, manufacturers and investors, the priority is to assess foreign-exchange utilization alongside factory output, capacity utilization, local-content ratios, input costs and operating margins. The evidence points to a changing industrial FX profile, but sustained gains in domestic production and competitiveness must be demonstrated through measurable improvements in industrial performance.
The decline coincided with a sharp increase in foreign-exchange utilization for manufactured products. That category rose to US$2.14 billion from US$1.03 billion, an increase of 107.4%, or US$1.11 billion.
| FX utilization category | H1 2025 | H1 2026 | Change |
| Industrial sector | US$4.72bn | US$3.72bn | −21.2% |
| Manufactured products | US$1.03bn | US$2.14bn | +107.4% |
The wider foreign-exchange picture also matters. Nairametrics reported that total FX utilisation reached US$7.61 billion in June 2026, up 78.1% from US$4.27 billion in June 2025. Import-related utilization increased to US$1.98 billion from US$1.84 billion, while manufactured-products utilization for June rose to US$447.94 million from US$291.76 million. The June figures are monthly totals, whereas the industrial-sector comparison covers six months. They cannot be substituted for one another, but they demonstrate why a decline in one category should not be interpreted as a general contraction in foreign-exchange demand.
Backward Integration: What the Figures Can and Cannot Prove
Industry analysts have identified local sourcing, backward integration and expanding export activity as possible explanations for the reduction in industrial-sector FX utilization. Ayokunle Olubunmi, head of Financial Institutions Ratings at Agusto & Co., told BusinessDay that some manufacturers were increasingly producing locally inputs they previously imported.
The commercial rationale is straightforward. When a manufacturer can obtain raw materials or intermediate goods from a competitive domestic supplier, it may reduce exposure to currency fluctuations, shipping costs and international supply disruptions. Companies that develop their own upstream production capacity may also gain greater control over input availability and production schedules. However, the aggregate FX data do not quantify how much of the decline resulted from local sourcing. They also do not isolate the effects of lower production, delayed purchases, changes in import prices or shifts in the timing of payments.
This distinction has direct consequences for industrial policy. If domestic production replaces imported inputs while factory output is maintained or expanded, the change could represent a structural improvement. If utilization falls because manufacturers cannot finance or obtain necessary materials, the same headline movement could signal a constraint on production. Establishing which explanation carries the most weight requires company-level evidence: imported-input expenditure relative to output, local-content ratios, capacity utilization, supplier reliability and the cost of comparable domestic and imported materials. Without those measures, backward integration remains a plausible explanation rather than a demonstrated national outcome.
Import Substitution Faces a Competitiveness Test
The increase in manufactured-products FX utilization complicates the argument that Nigeria is already achieving broad-based import substitution. It does not rule out progress in particular industries, but it shows that foreign-exchange demand across the reported categories is moving unevenly. Different industries can make different sourcing decisions simultaneously. A cement producer may increase local sourcing of certain inputs while another manufacturer imports machinery, components or finished products. Even within one company, domestic sourcing can expand in one production line while imports remain necessary elsewhere.
The policy challenge is therefore not simply to reduce imports. It is to build domestic suppliers that can meet industrial demand at competitive prices, with consistent quality and sufficient production capacity. Tariff protection or local-content requirements may encourage domestic investment, but they cannot guarantee that locally produced alternatives will be available, affordable or reliable. BusinessDay’s October 27 report also highlighted changes in Nigeria’s 2026 tariff structure, including higher protection for manufactured products alongside reductions affecting other categories. The increase in manufactured-products FX utilization suggests that the impact of tariff policy should be assessed against actual import behaviour and domestic supply capacity, rather than assumed from the policy’s stated objective.
For investors, the key question is whether local sourcing improves the economics of production. A lower foreign-exchange bill is beneficial only when it supports sustainable operating performance. Higher utilization, meanwhile, is not automatically negative if it finances machinery or inputs that enable future expansion.
Industrial Growth: Positive Output, Slower Momentum
Nigeria’s real GDP grew by 4.43% year on year in Q2 2026, up from 3.89% in Q1 2026 and 4.23% in Q2 2025, according to the National Bureau of Statistics. Manufacturing grew by 3.24%, compared with 1.69% in the corresponding quarter of 2025. The broader industrial sector recorded growth of 3.96%, down from 7.46% a year earlier. Manufacturing and the wider industrial sector are different statistical groupings, so their growth rates should be considered separately. The figures indicate that manufacturing expanded in real terms, but the broader industrial sector lost momentum. They do not establish whether individual manufacturers improved their margins, reduced costs or increased capacity utilization. Those outcomes depend on company-level performance and the conditions under which production took place.
Electricity supply is one important constraint. The Q2 GDP figures showed that electricity, gas, steam and air-conditioning supply contracted by 10.63%. The Manufacturers Association of Nigeria identified this weakness as a major concern in its response to the GDP report. For manufacturers, unreliable or expensive electricity can erode the advantages of domestic sourcing. A locally produced input may cost less than an imported alternative, but the savings can be undermined by generator fuel, production interruptions, idle labour and missed delivery schedules.
The industrial outlook therefore depends on more than foreign-exchange utilization. Energy reliability, logistics, financing costs, access to raw materials and final demand all influence whether manufacturers can convert investment into sustainable output growth.
September Business Activity: A Mixed Signal for Manufacturers
The Nigerian Economic Summit Group’s September 2026 Business Confidence Monitor offers a more recent view of operating conditions. Its Current Business Performance Index rose to 117.8 points from 112.7 in August, reaching a record high in the series reported by the group. Manufacturing’s own index moved in the opposite direction, falling from 120.4 points in August to 108.4 in September. It remained above the 102.5 points recorded in September 2025, but the monthly decline indicates that reported manufacturing activity moderated. Trade recorded the strongest sectoral performance in September, supported partly by stockpiling and back-to-school demand. This helped lift the composite index, but it should not be mistaken for an equivalent improvement across manufacturing.
NESG also reported that businesses continued to face financing constraints, irregular electricity supply, infrastructure bottlenecks, insecurity and high operating costs. Its Cost of Doing Business and Prices sub-indices remained below the neutral 100-point threshold, at 39.2 and 58.0 points respectively. These survey readings are not direct measurements of industrial production. They provide additional context, however, for an economy in which headline GDP is growing while manufacturers continue to report operating challenges.
Capital Allocation: The Measures That Matter
Manufacturers and investors should evaluate the FX data alongside indicators that show whether businesses are producing more efficiently and generating adequate returns. For manufacturers, the first priority is to compare the total delivered cost of domestic and imported inputs. Purchase prices alone are insufficient: quality, transportation, delivery reliability, storage requirements and payment terms can materially alter the economics of sourcing. The second priority is working-capital management. Manufacturers must often finance raw materials, energy and labour before receiving payment for finished goods. Expensive credit or delayed customer payments can limit production even when a local supplier offers a competitive price. Lower FX utilization should therefore be examined alongside inventory turnover, receivables, supplier credit and cash conversion.
For investors and lenders, relevant indicators include input costs relative to sales, operating margins, capacity utilization, capital expenditure, inventory movements and the proportion of materials sourced locally. Together, these measures can help distinguish genuine efficiency gains from reduced purchasing caused by operational or financial constraints. Government policy also has a role. Reliable electricity, transport infrastructure, access to long-term finance and predictable trade arrangements can make domestic suppliers more competitive. Support for local production is most effective when it expands viable capacity rather than simply changing the price incentives facing importers.
Bold Lite Industrial Outlook
Nigeria’s first-half 2026 figures reveal a substantial decline in industrial-sector FX utilization alongside a sharp increase in utilization for manufactured products. June’s broader FX data show that total utilization also rose significantly, while Q2 GDP and September business-confidence indicators point to uneven industrial momentum. The evidence supports a measured conclusion: Nigeria’s reported foreign-exchange utilization pattern is changing, but the available aggregate figures do not establish the extent to which local sourcing has reduced import dependence or improved industrial productivity. The next stage of assessment should connect FX utilization with import volumes, local-content ratios, factory output, capacity utilization and company-level input costs. That evidence would show whether domestic production is replacing imported inputs while maintaining competitiveness and expanding industrial capacity. Until those measures align, a reduction in one FX category should be treated as an important signal for further analysis—not as proof that Nigeria has completed a broad import-substitution transition.
References
- Local sourcing cuts manufacturers’ FX demand by $1bn – Businessday NG. (n.d.). BusinessDay. https://businessday.ng/business-economy/article/local-sourcing-cuts-manufacturers-fx-demand-by-1bn/
- Adigun, O. (2026, October 26). Nigeria’s FX spending hits record $7.61 billion as services drive 78% surge. Nairametrics. https://nairametrics.com/2026/10/26/nigerias-fx-spending-hits-record-7-61-billion-as-services-drive-78-surge/
- Odeniyi, S., & Odeniyi, S. (2026, August 31). Nigeria’s economy grows 4.43% in Q2 – NBS. Punch Newspapers. https://punchng.com/nigerias-economy-grows-4-43-in-q2-nbs/
- Odeniyi, S., & Odeniyi, S. (2026, August 31). Nigeria’s economy grows 4.43% in Q2 – NBS. Punch Newspapers. https://punchng.com/nigerias-economy-grows-4-43-in-q2-nbs/
- The Guardian Nigeria, September 4, 2026 — “MAN decries industrial sector GDP decline to 3.96%.” https://guardian.ng/business-services/man-decries-industrial-sector-gdp-decline-to-3-96/