
By Samuel Ugonna Benson, Lead Analyst | Bold Lite Agency
Nigeria’s economic recovery is entering a more complicated phase. A new capital tests. Headline inflation is falling and real GDP growth is accelerating. Whereas the foreign capital inflows have surged, yet the underlying cost of capital remains restrictive enough to force businesses and investors to rethink where every naira is deployed.
The latest inflation data from the National Bureau of Statistics (NBS). NBS put headline inflation at 15.43% in July, down from 15.91% in June and significantly below the 24.94% recorded in July 2025. On a month-on-month basis, inflation also moderated to 1.57% from 1.66% in June. That is genuine disinflation. But it is not the same thing as falling prices.
Prices are still going up. They are simply rising more slowly than before. That distinction matters for households, manufacturers and corporate treasury departments deciding whether the improvement is durable enough to support longer-term investment commitments.
Disinflation Meets a Still-Restrictive Monetary System
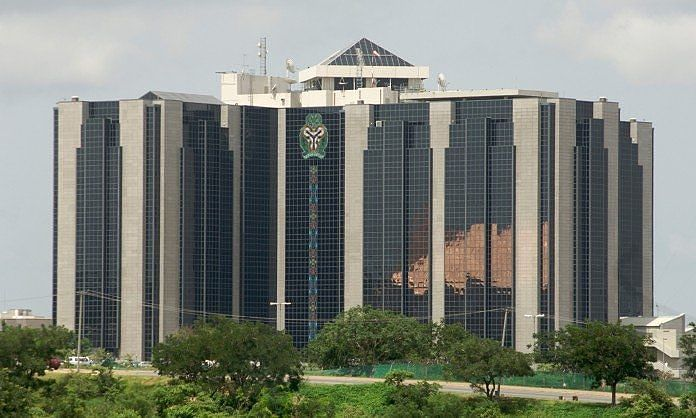
The Central Bank of Nigeria (CBN) has maintained the Monetary Policy Rate (MPR) at 26.5%, while the Cash Reserve Requirement for deposit money banks remains 45%. The policy settings show that the monetary authority continues to prioritise inflation management even as headline price growth moderates. No imagine what this could steam up. That creates an unusual investment environment. Inflation is moving downward, but the nominal cost of borrowing remains high. Companies cannot therefore assume that lower inflation will immediately translate into cheap commercial credit. If that’s visible is companies will beam rays
Banks still have to price credit according to funding costs. Regardless. Liquidity requirements, borrower risk, tenor and expected inflation. For businesses, this means that the strategic value of internally generated cash remains high even as the macroeconomic environment begins to look less hostile. Internal revenue generated cash value compared with the external market. The companies best positioned to exploit the next phase may not simply be those with access to the largest credit facilities. They may be those capable of turning existing cash into productive assets faster.
Foreign Capital Is Returning — But It Is Not Yet Broad-Based
The capital-importation numbers provide another important signal. Nigeria attracted $10.37 billion in foreign capital during Q1 2026, representing an 83.83% increase from the $5.64 billion recorded in Q1 2025 and a 60.97% increase from Q4 2025. At first glance, that looks like a sweeping vote of confidence, right.? The composition tells a more complicated story.
Portfolio investment accounted for $9.86 billion, or 95.09% of total capital imported, while foreign direct investment stood at only $135.08 million, representing 1.30%. Money-market instruments attracted $6.50 billion and bonds received $3.23 billion. This distinction is critical for capital allocation.
The Portfolio investors can respond rapidly to interest-rate differentials. Exchange-rate expectations and improvements in financial-market conditions. Direct investors typically require a much deeper commitment to factories, infrastructure, technology, employment and long-term operating assets. Nigeria therefore has evidence of returning foreign appetite. The actual next test is whether that appetite increasingly migrates from financial instruments into productive capacity.
GDP Growth Strengthens the Investment Case
The real economy is providing a more encouraging signal. Nigeria’s GDP expanded by 4.43% year-on-year in Q2 2026, improving from 3.89% in Q1 and 4.23% in the corresponding quarter of 2025. The services sector grew 4.60%, agriculture expanded 4.39%, while the non-oil economy grew 4.31%. But the composition again matters.
Industrial growth slowed to 3.96% from 7.46% a year earlier. Oil production improved to an average 1.72 million barrels per day, lifting oil-sector growth to 7.31%, yet oil represented only 4.16% of real GDP. The non-oil sector accounted for 95.84%. The message for investors is straightforward.
Nigeria’s growth story is becoming increasingly dependent on the ability of the non-oil economy to sustain expansion while industrial productivity catches up. This stipulates a clear income funnel source. That puts manufacturing, telecommunications, financial services, agriculture, construction and logistics directly inside the capital-allocation conversation.
Energy Costs Could Complicate the Disinflation Story
The moderation in headline inflation also faces an important test from energy costs. The recent movement in petrol prices, including the increase in Dangote Petroleum Refinery’s PMS gantry price to ₦1,350 per litre. This creates a potential cost channel through transportation and distribution. That does not automatically reverse the national disinflation trend, but it can create pressure in sectors where fuel represents a significant operating expense.
For manufacturers, logistics operators and agricultural distributors, the issue is not simply the pump price. It is fuel intensity. A business transporting goods over long distances with inefficient vehicles can experience much greater margin pressure than a competitor using route optimisation, consolidated deliveries and better asset utilisation. This is where treasury strategy begins to merge with operational strategy.
The New Capital Allocation Equation Expansion
The improving macroeconomic numbers create opportunities. But they do not justify indiscriminate expansion. Corporate boards need to distinguish between cheap-looking assets and productive assets. Observing due diligence. A lower inflation rate may improve planning visibility, but a 26.5% policy rate still makes poorly structured borrowing expensive. No lies about that.
Foreign portfolio inflows may deepen liquidity in financial markets. Meanwhile, their predominance also means capital can move quickly when risk perceptions change. Businesses therefore need a more strategic disciplined hierarchy. First comes liquidity protection. Then debt management. Then productive investment. Only after those foundations are secure should companies aggressively pursue expansion. The strongest opportunities are likely to emerge where businesses can reduce recurring operating costs. Which is probably quite challenging but possible achieve. While expanding productive capacity: energy efficiency, local sourcing, digital payments, logistics technology, agricultural processing and infrastructure-linked services all fit that model.
Bold Lite Strategic Outlook
Nigeria’s 15.43% inflation rate, 4.43% Q2 GDP growth and $10.37 billion Q1 capital-importation figure point to a macroeconomic environment that is improving without becoming risk-free. The key fundamental shift is not simply that inflation is falling. It appears that Investors are beginning to operate with clearer visibility across foreign exchange markets. The financial markets and real-sector growth. Yet the dominance of portfolio investment shows why policymakers and corporate leaders should avoid confusing short-term capital appetite with permanent productive investment. A determinant of sustainability. Over the next several quarters, Nigeria’s strongest economic advantage will come from converting financial-market confidence into factories, technology, infrastructure, jobs and higher domestic productivity. While protecting businesses from renewed energy, currency and financing shocks.