
By Samuel Ugonna Benson, CEO & Lead Analyst | Bold Lite Agency
Nigeria‘s manufacturing sector recorded 3.24% real growth in Q2 2026, while broader industrial growth slowed to 3.96% from 7.46% a year earlier and combined inventory held by a sample of NGX-listed manufacturing companies reached approximately ₦1.77 trillion, up 10.6% year-on-year. Over the same comparison, the companies’ combined cost of sales increased 13.7% to ₦1.434 trillion, while the electricity, gas, steam and air-conditioning supply segment contracted 10.63%. The inventory data does not establish that all ₦1.77 trillion represents finished products awaiting buyers. It represents reported inventories across the companies examined and therefore encompasses the accounting stock position rather than a pure warehouse measure of unsold finished goods. The more important signal is the simultaneous increase in inventory and cost of sales, which places greater emphasis on inventory turnover, working-capital velocity and the cash required to support production.
At the monetary end of the operating cycle, the Central Bank of Nigeria reduced the Monetary Policy Rate from 26.5% to 23% at its September 21–22, 2026 meeting. The 350-basis-point reduction changes the policy benchmark, but it does not establish an equivalent reduction in the effective borrowing costs faced by individual manufacturers.
Q2 2026 Industrial Ledger
| Industrial variable | Q2 2025 | Q2 2026 | Movement |
| Real GDP growth | 3.89% | 4.43% | +0.54 pp |
| Industrial-sector growth | 7.46% | 3.96% | -3.50 pp |
| Manufacturing real growth | 1.69% | 3.24% | +1.55 pp |
| Manufacturing inventory, selected NGX companies | ₦1.597tn* | ₦1.77tn | +10.6% |
| Cost of sales, selected NGX companies | ₦1.261tn* | ₦1.434tn | +13.7% |
| Electricity, gas, steam & air-conditioning supply | — | -10.63% | Contraction |
Download Institutional Data Model (CSV)
Comparable inventory and cost-of-sales figures reported for the selected companies’ Q1 2025 base period; they should not be treated as economy-wide manufacturing aggregates.
Inventory Velocity: Where ₦1.77 Trillion Becomes Operationally Significant
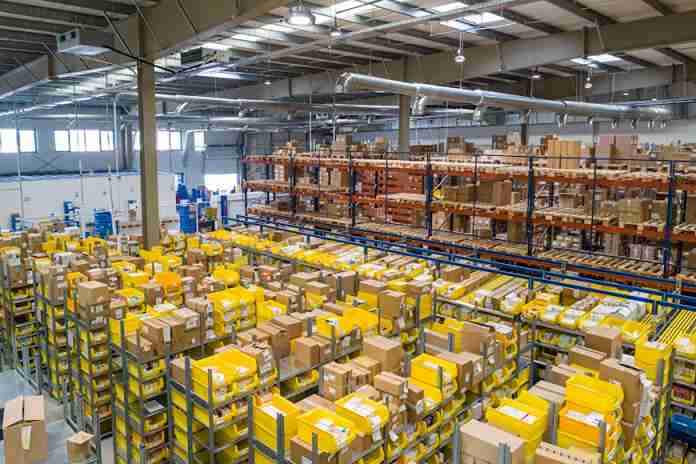
The central issue is not simply the size of the inventory balance. It is the speed at which that inventory converts back into cash. The selected NGX-listed manufacturers carried approximately ₦1.77 trillion in inventory, compared with roughly ₦1.597 trillion in the comparable prior-year period. At the same time, cost of sales rose from approximately ₦1.261 trillion to ₦1.434 trillion. That combination creates an important working-capital question.
Inventory can rise for legitimate operating reasons: higher raw-material requirements, precautionary stockholding, production expansion, seasonal procurement or changes in supplier conditions. It can also increase when finished products move more slowly through distribution channels. The balance-sheet implication is therefore determined by inventory turnover, not inventory size alone. Where inventory days expand faster than sales conversion, cash becomes immobilised inside the operating cycle. Procurement has already consumed liquidity, but the corresponding cash receipt has not yet returned to the treasury account. Financing costs continue while the stock remains on the balance sheet.
That is the measurable transmission mechanism behind inventory stress:
Procurement outflow → Inventory accumulation → Slower conversion → Cash trapped in stock → Reduced working-Capital flexibility.
Cost of Sales: The Second Side of the Inventory Equation
The 13.7% increase in cost of sales is particularly relevant because it exceeded the 10.6% inventory increase reported for the companies examined. This does not establish that manufacturers are overproducing. It does, however, show that the cost base attached to the reported inventory position has increased materially. For industrial finance teams, the resulting dashboard should separate three components:
Raw-material inventory: stock required to maintain production continuity. Work in progress: capital already committed to goods that have not reached saleable completion. Finished goods: completed output awaiting distribution and cash realisation. Each category has a different cash-conversion profile. Treating the entire ₦1.77 trillion as “unsold goods” obscures that distinction.
Energy Transmission: A Secondary but Material Margin Variable
The energy channel adds another layer to the working-capital equation. The 2026 domestic gas framework set the Domestic Base Price at $2.18/MMBtu, while commercial users were assigned a wholesale price of $2.68/MMBtu, compared with $2.63/MMBtu in 2025. The commercial increase is therefore approximately 1.9%. The gas adjustment itself is modest. The industrial concern is the aggregate conversion-cost stack created when gas, electricity, diesel-backed generation, maintenance and reliability costs are combined. The Q2 data shows the electricity, gas, steam and air-conditioning supply segment contracting 10.63%.
That contraction should not automatically be attributed to the gas-price adjustment; the data does not establish such causation. It does, however, identify energy supply as a relevant component of the industrial operating environment. For an energy-intensive factory, the appropriate management metric is therefore energy cost per unit of saleable output, not the movement of one tariff in isolation.
CapEx Compression: The Financing Hurdle
The CBN’s September decision reduced the MPR from 26.5% to 23%, a 350-basis-point reduction. The policy change lowers the central monetary benchmark, but actual manufacturing credit costs remain dependent on lender pricing, borrower risk, collateral and facility structure.
This distinction matters for CapEx. A machinery acquisition must generate enough incremental operating cash flow to cover depreciation, maintenance, energy consumption, financing and the working capital associated with the additional production volume. If the projected return on the asset does not sufficiently exceed the effective financing and operating hurdle, management can defer the investment without necessarily reducing current production. The result is CapEx compression rather than immediate industrial contraction: machinery replacement is delayed, automation projects are sequenced later, maintenance cycles may be extended and new production capacity is subjected to a higher investment threshold.
Industrial Transmission Matrix
Macro-Industrial Desk Analysis: Data registers tracking real-sector performance confirm that Nigeria’s manufacturing sector recorded a 3.24% real year-on-year growth in Q2 2026, while broader industrial growth slowed to 3.96% from 7.46% a year earlier. Concurrently, sample data from a select group of NGX-listed manufacturing companies reveals that combined accounting inventories reached approximately ₦1.77 trillion (up 10.6% YoY), while their combined cost of sales jumped 13.7% to ₦1.434 trillion. This data-dense brief parses the macro transmission channels: evaluating the 10.63% contraction across utility energy segments, analyzing the real-world impact of the September 305-basis-point MPR cut to 23%, and establishing the exact balance-sheet control metrics required to optimize cash-conversion velocities. — S.U.B.
The current data supports three separate control variables:
- Inventory cash-conversion velocity: How rapidly raw materials, work in progress and finished goods return capital to the treasury through sales.
- Energy conversion cost: How much energy expenditure is required to generate each additional unit of saleable output.
- CapEx conversion spread: Whether the incremental cash generated by a new productive asset sufficiently exceeds its financing and operating requirements. These variables should not be collapsed into a single “industrial crisis” indicator. Each represents a separate balance-sheet pressure and requires a different management response.
Bold Lite Q4 Operating Outlook Nigeria’s industrial ledger presents a mixed signal. Manufacturing expanded by 3.24% in real terms in Q2 2026, but broader industrial growth slowed to 3.96%, while the selected listed manufacturers accumulated approximately ₦1.77 trillion in inventory. The immediate issue for corporate treasuries is therefore not inventory volume alone. It is whether the stock can be converted into cash quickly enough to finance the next procurement cycle, service obligations and sustain production. The September MPR reduction provides a lower policy benchmark, but its industrial effect will depend on transmission into actual credit pricing. Meanwhile, energy costs remain embedded in factory conversion economics, making unit-level productivity more important than headline tariff movements.
For Nigerian manufacturers, the critical Q4 dashboard should consequently centre on inventory days, cost of sales, receivable days, energy cost per unit, machine utilisation and effective financing cost. The ₦1.77 trillion figure is significant not because every naira represents dead stock, but because it represents capital that must continuously move through the production-and-sales cycle before it becomes available for the next operating requirement.