
By Samuel Ugonna Benson, CEO & Lead Analyst | Bold Lite Agency
Industrial Analytics Desk | Q4 2026
Nigeria’s manufacturing sector enters Q4 2026 with 3.24% real year-on-year growth in Q2, while broader industrial growth slowed to 3.96% from 7.46% a year earlier and manufacturing’s share of real GDP declined to 7.72%. The electricity, gas, steam and air-conditioning supply segment contracted by 10.63%, highlighting a widening gap between aggregate economic expansion and the performance of a critical industrial input. The energy-cost picture is more measured than the earlier 42.1% claim suggested. Effective 1 April 2026, the domestic base price for natural gas rose from $2.13 to $2.18/MMBtu, while commercial users moved from $2.63 to $2.68/MMBtu, an increase of about 1.9%. The larger industrial issue is therefore the cumulative cost of maintaining reliable production across gas, electricity, backup generation, logistics and equipment rather than the gas-price adjustment in isolation.— S.U.B
At the financing end of the transmission chain, the Central Bank of Nigeria reduced the Monetary Policy Rate from 26.5% to 23% at its 21–22 September 2026 MPC meeting. That is a material change in the policy benchmark, but it does not mean manufacturers immediately receive 23% credit; effective borrowing costs continue to depend on bank pricing, borrower risk, collateral and facility structure.
Quick Brief
- Industrial output: Manufacturing grew 3.24% in Q2 2026, below the 4.43% real GDP growth rate, while industrial growth slowed to 3.96%.
- Energy: Commercial gas pricing moved to $2.68/MMBtu from $2.63/MMBtu, while the electricity, gas, steam and air-conditioning segment contracted 10.63% in Q2.
- Capital: The MPR was reset to 23% in September from 26.5%, potentially reducing the monetary hurdle for new borrowing while leaving actual corporate lending costs market-dependent.
Energy & Infrastructure Tariffs: The Conversion-Cost Problem
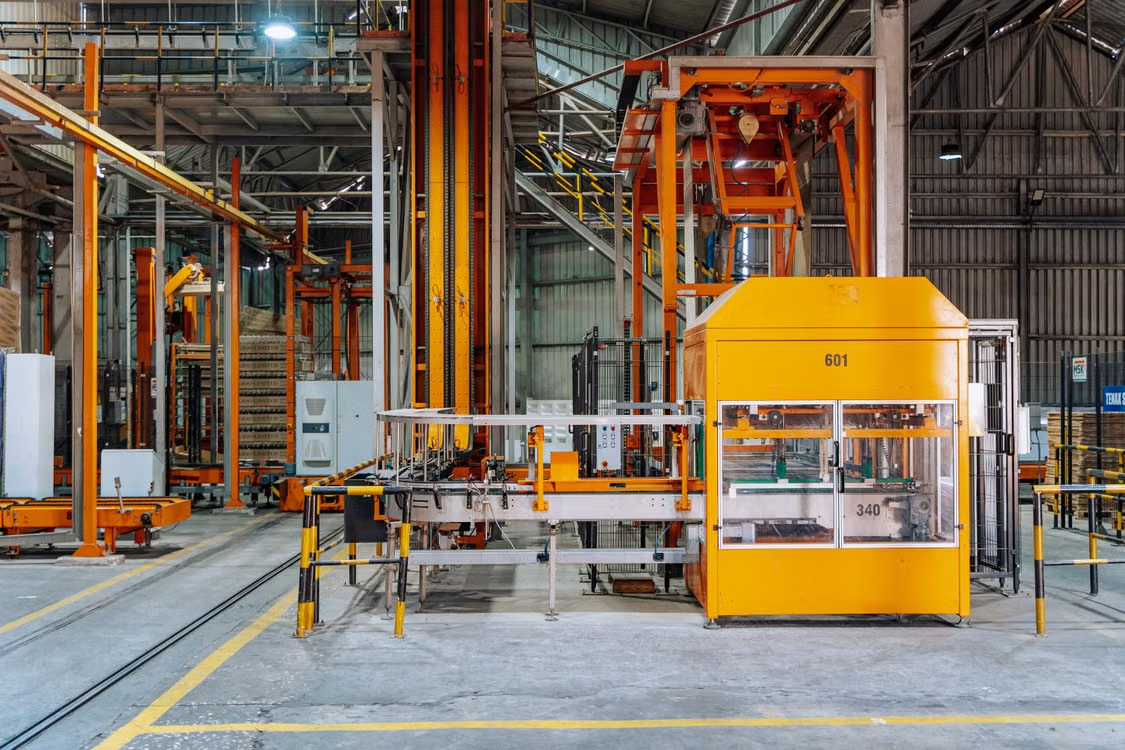
For an energy-intensive manufacturer, the relevant variable is not the published gas price alone. It is the energy cost embedded in each unit of saleable output. The April gas adjustment was modest in percentage terms, but Nigerian factories frequently operate with a mixed energy stack. Gas may supply process heat or captive generation, while grid electricity, diesel generation, compressors, transformers and maintenance expenditure fill reliability gaps. Each additional layer increases the cost of keeping installed production capacity available.
The Q2 industrial data provides an important signal. Electricity, gas, steam and air-conditioning supply contracted 10.63%, while the wider industrial sector expanded only 3.96%. The data does not establish that gas pricing caused the contraction, but it demonstrates that the energy-supply segment itself was weakening while industrial output remained positive.
That distinction matters for factory economics. A plant can maintain nominal output while absorbing higher conversion costs through reduced margins. Alternatively, management can protect margins by adjusting production schedules, substituting energy sources, increasing maintenance intervals or prioritising product lines with higher contribution margins. The operational metric should therefore be energy cost per unit of output, measured against machine-hour utilisation and gross contribution.
CapEx Compression: Financing Determines the Expansion Threshold
The September monetary-policy adjustment changes the financing environment, but the industrial transmission mechanism operates through the spread between the cost of capital and the expected return from additional productive capacity. The CBN reduced the MPR to 23% from 26.5%, following its September 21–22 meeting. The change lowers the policy benchmark by 350 basis points, but manufacturers’ actual borrowing costs depend on commercial-bank pricing and individual credit conditions. For a manufacturer evaluating a new production line, the investment calculation extends beyond the machine purchase price. Management must account for installation, imported components, foreign-exchange exposure, financing charges, maintenance, energy consumption and the working capital required to support higher throughput.
This produces a straightforward capital-allocation test: Incremental throughput must generate sufficient cash flow to cover incremental capital cost, financing cost and operating cost. Where that return is inadequate, management can rationally defer automation, machinery replacement or plant expansion even while existing facilities continue operating. That is CapEx compression: not necessarily a shutdown of investment, but a higher hurdle for converting corporate cash into fixed productive assets.
Inventory Cash-Conversion Velocity: The Working-Capital Constraint
The inventory problem begins when procurement teams must decide how much raw material to hold against uncertain supply conditions. Imported inputs introduce additional variables: supplier lead times, shipping schedules, port handling, foreign-exchange exposure and local distribution. Holding too little inventory exposes production to line stoppages; holding too much converts cash into stock that may remain idle while financing costs continue to accrue.
The relevant control metric is therefore not simply inventory volume. It is the relationship between inventory days, supplier lead-time latency and production downtime risk. A factory carrying 60 days of critical inputs may have stronger production protection than one carrying 20 days, but that protection has a financing cost. Conversely, aggressive inventory reduction may improve short-term cash liquidity while increasing the probability of production interruption. The optimal position is the lowest inventory level capable of maintaining the required production schedule at an acceptable supply-disruption probability. This is where cash-conversion velocity becomes an industrial productivity measure rather than a retail metric.
Demand, Pricing Power and Margin Retention
Manufacturers also face a limit on how much of their higher conversion costs can be transferred to customers. Q2 2026 real GDP grew 4.43%, while manufacturing expanded 3.24%. The difference matters because manufacturers operate inside the broader demand system: higher production costs can be passed through only where customers have sufficient purchasing capacity and competing suppliers do not constrain pricing.
Where price increases reduce volumes, factories face an additional problem: fixed production costs are spread across fewer units. That makes capacity utilisation economically significant even when no official plant-level utilisation figure is available. A manufacturer with high fixed costs needs sufficient throughput to dilute depreciation, labour, maintenance and plant overhead across output. The strategic question is consequently not whether a company can raise prices. It is whether the resulting price-volume combination preserves contribution margin and keeps the production asset economically utilised.
Industrial Operating Matrix
The current Nigerian manufacturing environment can be reduced to three linked operating variables:
Energy: What does each additional unit of output cost to power and process?
Capital: What return must a new machine or plant generate before management approves the investment?
Inventory: How much working capital must be immobilised to prevent supply-chain latency from stopping production?
These variables interact. Higher energy costs reduce operating cash flow; weaker cash flow raises the internal hurdle for CapEx; deferred investment can constrain productivity; and tighter working capital can force lower inventory buffers. The resulting pressure appears in margins and throughput rather than necessarily in an immediate contraction of headline output.
Bold Lite Strategic Outlook
Nigeria’s Q2 2026 data presents an uneven industrial picture: manufacturing continued to expand in real terms, but its growth remained below aggregate GDP growth, while broader industrial expansion slowed substantially from the previous year. The policy environment has also changed. The MPR reduction to 23% provides a lower monetary benchmark than the 26.5% rate maintained through July, while the April gas-price adjustment was comparatively small at the commercial-user level. For factory management, the immediate priority is therefore measurement rather than broad expansion assumptions.
The core dashboard should track:
Energy cost per unit + Machine-hour utilisation + Raw-material days + Production downtime + Financing cost + Inventory turnover.
That combination provides a more useful assessment of industrial resilience than headline GDP growth alone. It shows whether additional working capital is producing additional saleable output, whether installed assets are being adequately utilised, and whether operating cash flow can support the next investment cycle.
Primary Sources & Industrial Registries Portal
- National GDP and manufacturing statistics: National Bureau of Statistics — GDP Data Repository
- Manufacturing-sector research and capacity indicators: Manufacturers Association of Nigeria — Economic Reviews
- Monetary policy and interest-rate decisions: Central Bank of Nigeria — Monetary Policy Decisions
- Natural-gas regulatory framework: Nigerian Midstream and Downstream Petroleum Regulatory Authority
- Electricity-market regulation: Nigerian Electricity Regulatory Commission