
BOLD LITE TERMINAL | INDUSTRIAL CAPACITY & LOGISTICS REPORT
Date of Release: October 7, 2026 | Desk Code: BLA-IND-2026-N36
“Data registers tracking real-sector import frameworks confirm that West Africa’s primary trade gateways face intense working-capital and logistics latency headwinds entering Q4 2026. Nigeria’s import-dependent industrial system enters the quarter with three measurable operating variables moving through the same balance-sheet channel: the Nigeria Customs Service (NCS) currently displays a ₦1,383.63/$ selling reference rate, Nigerian ports handled 68.2 million metric tonnes of cargo in H1 2026, and the Central Bank’s latest Nigerian Overnight Financing Rate (NOFR) stood at 20.00% on October 5. This policy diagnostic evaluates the precise quantitative variables defining the real-sector supply squeeze: parsing the structural transmission of the updated FX customs valuation rate, auditing the expanding vessel turnaround times across national port nodes, and analyzing how compounding terminal landing tariffs interact with the raw cash-conversion velocities of listed manufacturing conglomerates.” — S.U.B.
Nigeria’s import-dependent industrial system enters Q4 2026 with three measurable operating variables moving through the same balance-sheet channel: the Nigeria Customs Service currently displays a ₦1,383.63/$ selling reference rate, Nigerian ports handled 68.2 million metric tonnes of cargo in H1 2026, and the Central Bank’s latest Nigerian Overnight Financing Rate stood at 20.00% on October 5. The interaction between customs valuation, cargo velocity and financing cost now matters more than any single headline tariff movement.
The policy architecture has also changed. The Nigeria Customs Service does not independently determine the foreign-exchange rate used for customs valuation. Its B’Odogwu platform receives official FX rates transmitted by the Central Bank of Nigeria, meaning import-cost analysis must distinguish between FX valuation, statutory tariff rates and physical port charges rather than treating them as one policy variable.
That is the relevant ledger for manufacturers, assemblers, distributors and other import-dependent operators.
Trade Logistics Data Note: This downloadable data register provides a robust operational framework for auditing shipment-level port velocity and calculating final landed input costs in Nigeria. Designed as a structured industrial tool, the matrix bridges macroeconomic indices—including Nigeria Customs Service (NCS) valuation selling references and short-term term-funding benchmarks (30-day and 90-day NOFRI)—with real-world port performance trends and customized corporate inventory metrics.
The industrial transmission chain is therefore:
FX Valuation → Customs Liability → Landed Input Cost → Clearance Velocity → Inventory Holding Period → Financing Exposure → Production Cash Conversion.
The Customs-FX Disconnect
The central correction to Nigeria’s import-cost debate is institutional. Customs does not independently manufacture the exchange rate applied to import and export valuation. NCS has stated that its B’Odogwu unified customs-management system receives FX rates electronically from the CBN and applies them to customs transactions. The current NCS reference table displays a US dollar selling rate of ₦1,383.63, while the CBN’s latest displayed NFEM rate is ₦1,329.51. These figures should not be treated as competing “official rates” without reference to their separate purposes.
For industrial procurement desks, the distinction is material. A customs liability is determined through the applicable customs valuation framework, tariff classification and statutory duty treatment. The FX component then determines the naira equivalent of the foreign-currency value used within that assessment. The correct management question is therefore not:
“What new tariff has Customs imposed?” It is: “How does the applicable valuation rate alter the naira cost of a shipment already embedded in the procurement pipeline?” That distinction prevents an FX valuation movement from being incorrectly reported as a tariff increase.
Port Throughput Is Expanding
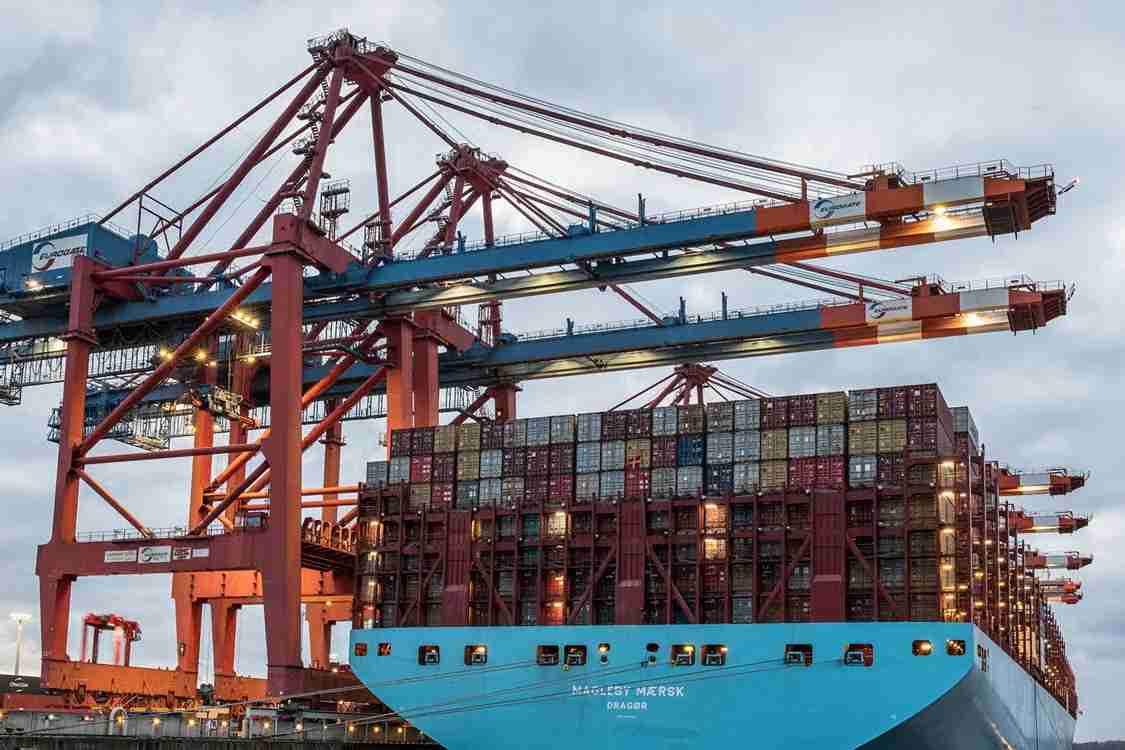
The physical trade system is carrying more cargo. Nigerian ports handled 68.2 million metric tonnes in H1 2026, compared with 60.8 million tonnes in H1 2025, representing a 12.2% increase. Ship calls reached 2,300, up 6.9%, while gross registered tonnage rose 20.9% to 96.6 million tonnes. Container traffic also increased 10.3% to 815,236 TEUs, with imports accounting for approximately 67% of container traffic. The critical efficiency signal, however, is vessel turnaround. NPA’s H1 2026 figures show average vessel turnaround worsening from 5.0 days to 5.3 days, while berth occupancy increased to 36.1%. That creates a more useful industrial question than an unsupported national cargo-dwell average: Is port capacity expanding faster than the operational velocity required to process the additional trade?
Higher throughput is economically positive. But when volume rises alongside longer turnaround, manufacturers and shipping operators must monitor whether infrastructure and clearance systems are keeping pace with cargo growth.
Clearance Velocity Is a Capital Variable
For an importer, cargo does not become economically productive when it arrives at anchorage. It becomes productive when the shipment has completed the necessary valuation, documentation, examination, release and inland evacuation processes and reaches the point of productive use. This creates a measurable operating interval: Cargo Discharge → Customs Processing → Release → Gate-Out → Factory Receipt.
Every additional day within that chain can increase exposure to storage, financing and scheduling costs. The NCS Authorised Economic Operator programme provides a useful empirical benchmark. Among 51 certified entities, Customs reported that average cargo clearance time fell from 168 hours to 41 hours, while demurrage payments declined by 90%. The implication is straightforward. Trade facilitation is not merely an administrative reform. Faster clearance can change the amount of capital required to sustain the same level of imported inventory.
The Working-Capital Transmission
The import ledger ultimately reaches corporate treasury. A company paying for imported production material must finance the period between supplier settlement and the eventual conversion of that material into revenue. The longer that interval becomes, the greater the amount of capital tied up outside productive circulation. The operational equation is:
Working-Capital Exposure = Imported Input Value × Holding Period × Effective Funding Cost
This should not be confused with the MPR. The CBN reset the MPR to 23% in September 2026, from 26.5%, while the latest NOFR was 20%. The 30-day and 90-day NOFRI readings stood at 21.31% and 22.31%, respectively, on October 6. These market benchmarks indicate the direction of short-term funding conditions, but they are not equivalent to the effective borrowing rate paid by an individual manufacturer. Corporate funding costs still depend on credit quality, collateral, tenor, lender pricing and facility structure. The industrial audit should therefore capture the company’s actual financing cost rather than substitute MPR for the cost of capital.
Import Costs Must Be Audited Per Unit of Output
A rising customs valuation does not automatically produce an equivalent rise in final product prices. The actual transmission depends on the composition of the shipment. For a manufacturer, the relevant calculation is:
Landed Input Cost = Customs Liability + Freight + Insurance + Terminal Charges + Inland Transport + Other Statutory Costs
That figure should then be divided by usable production output rather than simply by container count. A container carrying a high-value specialized component and one carrying low-value bulk inputs have completely different economic profiles. Industrial procurement teams should therefore monitor: “Landed Cost Per Usable Unit.” Rather than rely on a headline percentage increase in customs charges. This metric connects maritime expenditure directly to factory conversion economics.
The Import-to-Cash Conversion Audit
The most important supply-chain metric is not cargo volume alone. It is the speed at which imported capital becomes saleable output and then collected cash. Together they determine the effective import-to-cash cycle. This distinction is important because faster port clearance does not automatically create faster corporate cash conversion. A company can clear cargo quickly and still carry excessive raw-material inventory or face slow customer collections. The port is therefore one link in the capital cycle, not the entire cycle.
Four intervals should be tracked independently:
- Customs Clearance Days — time from cargo processing to release.
- Inland Transit Days — time from port gate-out to factory or distribution centre.
- Production Conversion Days — time between receipt of material and completion of saleable output.
- Receivable Days — time between sale and cash collection.
Strategic Industrial Response
Manufacturers should respond to maritime and valuation volatility through measurement rather than blanket import substitution. Three board-level controls are particularly important.
First: Customs Exposure Mapping. Procurement teams should identify which imported inputs are most sensitive to FX valuation, tariff classification and statutory changes. Second: Clearance-Velocity Benchmarking. Companies should maintain shipment-level records from discharge through gate-out and compare actual performance against internal targets. Third: Inventory Buffer Optimization. Safety stock should be determined by supply reliability, lead-time variability and production criticality rather than by arbitrary inventory multiples. The objective is not to minimize inventory at all costs. It is to minimize the amount of capital required to maintain a given level of production reliability.
Bold Lite Strategic Outlook
Nigeria’s maritime-industrial equation is entering a more measurable phase. Port activity is expanding. H1 2026 cargo throughput rose 12.2%, container traffic increased 10.3%, and vessel traffic rose 6.9%. At the same time, average vessel turnaround moved from five days to 5.3 days. The data therefore presents a mixed signal: “trade volumes are growing, but operating velocity remains a critical constraint.” The customs side carries a similar distinction. The NCS reference exchange rate affects the naira valuation of foreign-currency-denominated transactions, but it should not be mislabelled as a tariff. The applicable tariff remains a separate fiscal variable. For industrial boards, the priority is integration; “Customs valuation must connect to procurement, Port velocity must connect to inventory, Inventory must connect to financing, Financing must connect to production and Production must connect to cash recovery.”
The competitive advantage will accrue to companies that can measure those links at shipment level and adjust procurement, inventory and financing decisions before logistics friction reaches the factory floor. Nigeria’s port modernization and National Single Window initiatives could reduce administrative friction, but their industrial value should ultimately be judged through observable changes in clearance time, turnaround, cargo processing and total landed cost. The Q4 2026 industrial dashboard should therefore centre on five variables: Customs Valuation, Clearance Days, Landed Cost, Inventory Days, and Cash-Conversion Velocity. That is the more defensible measure of maritime friction in Nigeria’s industrial economy.
Primary Sources & Regulatory Citations Registry
- Nigeria Customs Service — Exchange Rate Register — current customs reference rates.
- Nigeria Customs Service — Customs Valuation Framework — valuation methodology and legal framework.
- Central Bank of Nigeria — Monetary Policy Decisions — September 2026 MPR reset.
- Central Bank of Nigeria — NOFR Data — latest overnight funding benchmark and NOFRI.
- Nigerian Ports Authority — port statistics, procedures and operational publications.
- NBS Foreign Trade in Goods Statistics — Q2 2026 foreign-trade dataset.