
By Samuel Ugonna Benson, Lead Analyst | Bold Lite Agency
Lead Analyst’s Note: “For years, West Africa’s real-sector treasurers have watched fiscal spending and central bank interest rates work at brutal cross-purposes. This new MoU is not just paperwork; it is a long-overdue structural alignment. At Bold Lite, our daily data monitoring has consistently shown that uncoordinated public liquidity injections dilute monetary policy transmission and punish private sector credit lines. This accord is the first step toward treating Nigeria’s financial ecosystem as a single, connected pipeline rather than isolated administrative fiefdoms.” — S.U.B.
Nigeria has spent years managing fiscal borrowing and monetary policy as separate instruments even though the market does not treat them separately. Government borrowing changes liquidity. Liquidity influences yields and financing conditions. Interest rates then feed into the cost of credit for banks, manufacturers, traders and households.
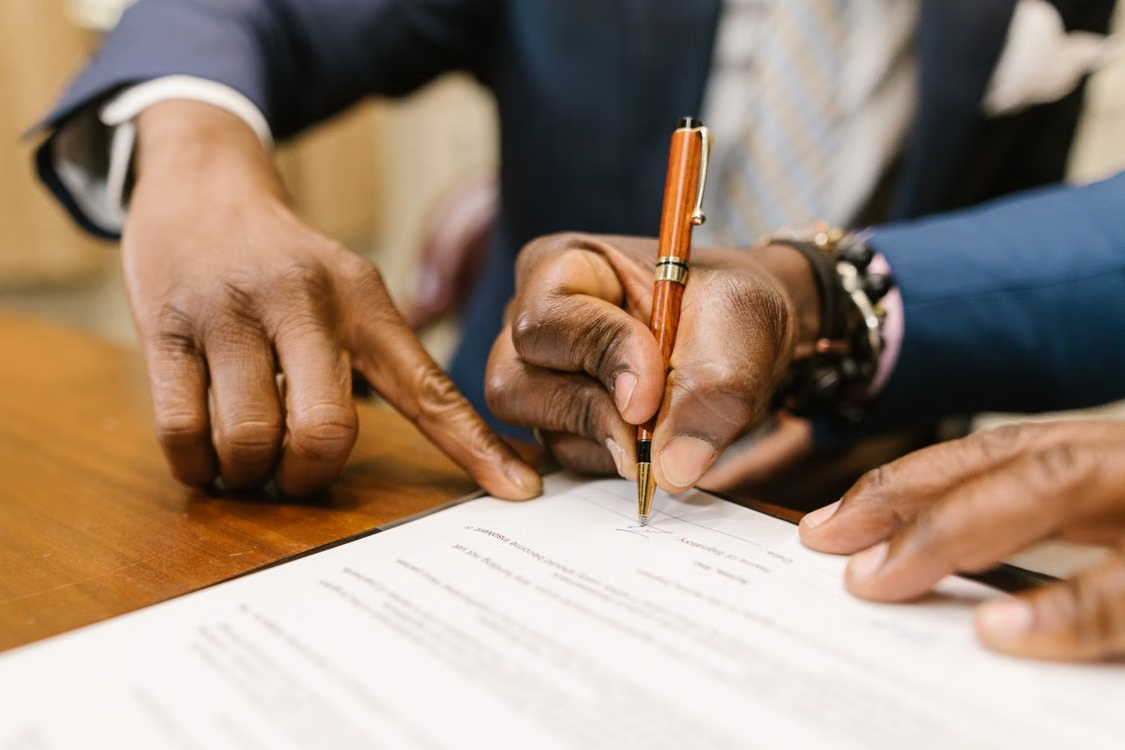
That interaction is the real economic story behind the Federal Ministry of Finance and Central Bank of Nigeria‘s new Memorandum of Understanding. Signed on September 18, the agreement provides for regular consultation, information sharing, joint policy assessment, liquidity forecasting, government cash management, debt-issuance planning and broader macroeconomic analysis. Finance Minister Taiwo Oyedele said the arrangement is designed to make coordination less dependent on the personalities occupying public offices.
The Cost of Working at Cross-Purposes
The fiscal authority and the central bank have different mandates, but their decisions meet in the same financial system. When government raises financing, the operation can affect liquidity and money-market conditions. When the CBN changes its monetary stance, the resulting interest-rate environment can alter the government’s own financing costs.
That feedback loop matters because Nigeria is operating with a high monetary-policy rate. At its July 2026 meeting, the CBN’s 306th MPC retained the MPR at 26.5 per cent and kept the CRR for deposit money banks at 45 per cent. The implication is straightforward: fiscal planning cannot be treated as an isolated budget exercise when every major borrowing decision interacts with the price and availability of money.
Where Government Borrowing Meets Private Credit
The private sector sits directly downstream of this relationship. If government financing absorbs a large share of available liquidity or pushes market yields higher, banks and investors reassess the return they require elsewhere. Companies seeking working capital, expansion finance or long-term investment then face a different funding environment. This is why the MoU’s provisions on debt issuance, government cash positions and liquidity forecasting matter more than the signing ceremony itself. The objective is to give both institutions a clearer picture of how fiscal operations and monetary conditions interact before those effects become market problems.
CBN Deputy Governor Sani Abdullahi said the framework will include joint technical analysis, scenario planning and stress testing around issues affecting both fiscal and monetary policy. That approach becomes particularly relevant for an oil-dependent economy where changes in crude prices can alter government revenue and foreign-exchange inflows at the same time.
Inflation Becomes a Wider Economic Problem
The agreement also reflects a shift in how Nigeria is approaching inflation. The CBN is transitioning toward an inflation-targeting framework, which places greater emphasis on forward-looking forecasts, transparent communication and anchoring inflation expectations. The Bank itself identifies stronger fiscal-monetary coordination as one of the supporting pillars of that transition. But inflation in Nigeria does not originate exclusively from monetary conditions.
Food supply, transport costs, energy prices, exchange-rate movements, logistics and imported inputs can all influence the final price consumers face. Oyedele acknowledged this broader supply-side dimension, pointing to agricultural productivity, food reserves, irrigation, climate resilience and transport infrastructure as areas where fiscal action can influence inflation. That changes the policy conversation. The CBN can influence financial conditions. It cannot build rural roads, increase farm yields or improve food distribution by itself.
Coordination Has a Red Line
There is, however, a boundary that the new framework cannot erase. The Finance Ministry needs to understand the monetary consequences of its decisions. The CBN needs to understand the fiscal environment in which monetary policy operates. Neither requirement means the central bank should become an extension of the Treasury. Oyedele explicitly said CBN operational independence remains intact and that coordination must not become fiscal dominance. Cardoso likewise described the agreement as a formal structure for collaboration while retaining the Bank’s responsibilities for price and financial-system stability.
That distinction will matter most when fiscal priorities and inflation objectives pull in different directions. A government may need to accelerate spending during a period when monetary authorities would prefer weaker demand. The Treasury may seek financing when market conditions are already tight. The central bank may need to maintain restrictive conditions even when businesses are demanding cheaper credit. The value of the framework will therefore depend on whether disagreement can be managed with data rather than concealed through institutional pressure.
The Data Behind the Decisions
One of the more consequential elements of the agreement is its emphasis on a common evidence base. The institutions are expected to exchange information covering government cash positions, financing plans, credit growth and foreign-exchange flows. The Finance Ministry is also working with the National Bureau of Statistics on additional economic indicators, including producer prices, employment and productivity.
Better data will not automatically produce better policy. It does, however, reduce the danger of one institution responding to an economic shock without seeing the fiscal or financial consequences unfolding elsewhere.
That matters in an economy where an oil-price shock, for example, can simultaneously change government revenue, foreign-exchange supply, domestic fuel economics, inflation expectations and monetary conditions. The policy response becomes stronger when those connections are visible before the shock reaches balance sheets.
What Businesses Should Watch
For businesses, the significance of the MoU will eventually appear through financial conditions rather than government statements. Treasurers will watch government borrowing schedules. Banks will watch liquidity and credit demand. Investors will watch yields and inflation expectations. Manufacturers will watch the cost and availability of working capital.
Those variables provide a more useful measure of the framework’s economic value than the number of meetings held between officials. The CBN’s own macroeconomic outlook has already linked effective fiscal-monetary coordination with exchange-rate stability, inflation control, job creation and stronger growth, while stressing that the outlook depends on consistent and well-sequenced policies. The distinction is important: coordination creates the mechanism. Economic outcomes still depend on execution.
From Agreement to Economic Operating System
Nigeria’s new fiscal-monetary arrangement is therefore less about creating another committee and more about changing how major economic decisions interact. The stronger model is one in which government borrowing is assessed alongside liquidity conditions, inflation risks and private-sector financing; monetary decisions are made with a clearer view of fiscal operations; and both institutions work from shared data without surrendering their separate mandates.
That would give the Nigerian economy something more valuable than another policy announcement: greater predictability. The real measure will come through the numbers that businesses and investors can observe—borrowing costs, credit availability, inflation expectations, liquidity conditions, exchange-rate stability and the behaviour of government securities. If those variables improve without weakening central-bank independence, the MoU will have moved beyond paperwork into economic infrastructure.
Bold Lite Strategic Outlook
Nigeria is moving toward a policy model in which fiscal decisions and monetary conditions are analysed as connected parts of one financial system. The immediate opportunity is better forecasting of liquidity, borrowing requirements and inflation pressures before they transmit into private-sector financing costs. The harder task will be maintaining that coordination when government financing needs conflict with the CBN’s price-stability objectives. For businesses, the most important signal will not be the MoU itself but whether policy consistency gradually lowers uncertainty around the cost and availability of capital.
Primary Sources & Regulatory Citations Registry
To maintain absolute institutional data transparency, the core variables, statutory timelines, and regulatory frameworks detailed in this macro briefing are drawn directly from the following official networks:
Fiscal-Monetary Coordination Directives: Formally verified via the [Federal Ministry of Finance Official Policy Releases Portal](https://proshare.co “Finance Ministry Statements”) and the policy frameworks on the [Proshare Economy Reports Hub](https://proshare.co “Proshare Archive”).
National Monetary Aggregates: Broad money supply indices (M3) and external reserve trackers are monitored live on the **[Central Bank of Nigeria (CBN) Data Center](https://channelstv.com “CBN Economic Indices Portal”)**.