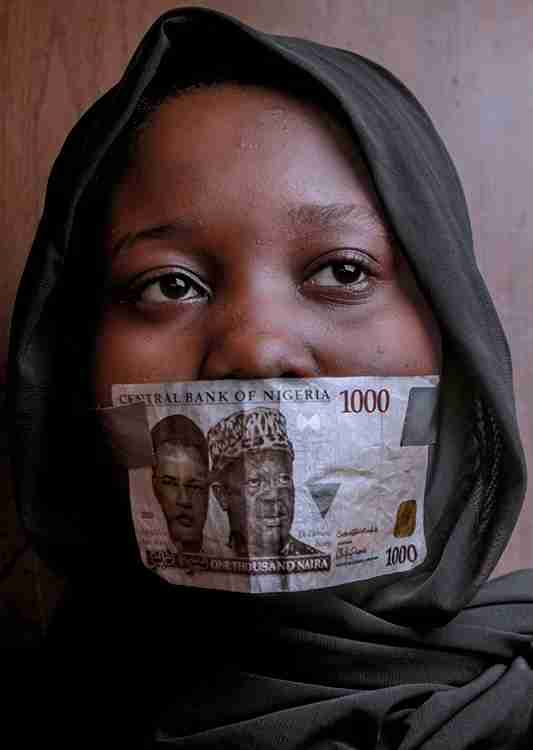

“Nigeria’s cash-transfer intervention offers immediate household relief, but its wider economic value depends on funding transparency, monetary conditions and the ability of domestic production to respond to additional demand.” The Federal Government’s National Emergency Relief and stabilization Intervention (NERSI) introduces a ₦50,000 cash grant for selected vulnerable households. Delivered through digital payment providers, the programme is intended to cushion the impact of living costs on household finances. Its macroeconomic significance lies in the relationship between public expenditure, consumer purchasing power and domestic supply capacity. A cash transfer can support demand, but the extent to which that spending translates into higher output or additional price pressure depends on the scale of disbursement, the source of funding and the responsiveness of local markets. The central issue is therefore not whether the grant represents an injection of purchasing power. It does. The question is whether the economy can accommodate the resulting expenditure without eroding the real value of the support through higher prices.
The real test of NERSI is not the amount announced, but the purchasing power preserved and the economic activity its delivery can demonstrably support. — S.U.B.
Fiscal injections and the M2 transmission question
The relationship between NERSI and broad money supply (M2) requires careful examination. When government payments reach beneficiaries’ bank accounts or digital wallets, household purchasing power increases. The funds can then circulate through retail transactions, merchant accounts, supplier payments and other commercial activities.
However, a fiscal transfer does not automatically translate into an equivalent expansion of M2. The monetary effect depends on how the expenditure is financed, movements in government deposits, banking-system settlement and subsequent changes in deposits and currency holdings. A transfer financed from existing government balances has a different monetary profile from expenditure supported by new borrowing or monetary financing. Establishing its effect requires comparing actual disbursements with CBN monetary aggregates over the relevant period.
The available NERSI information does not provide an aggregate payment value or a beneficiary-level disbursement series sufficient to quantify this relationship. Consequently, describing the programme as a major driver of M2 expansion would go beyond the available evidence. For macroeconomic monitoring, the relevant indicators are the value and timing of government transfers, currency in circulation, bank deposits and the growth of broad money. These measures would help establish whether the intervention has materially altered system liquidity.
Monetary restraint and the cost of productive capacity
The CBN’s September 21–22, 2026 Monetary Policy Committee meeting reset the Monetary Policy Rate at 23%. It retained the Cash Reserve Requirement at 45% for deposit money banks, 16% for merchant banks and 75% for non-TSA public-sector deposits. These measures form part of the monetary framework within which NERSI is being implemented. The MPR provides the benchmark for monetary policy, while reserve requirements influence the funds banks must maintain against specified deposit liabilities. For businesses, the relevant transmission question is how these conditions affect the availability and cost of credit. Manufacturers and distributors facing expensive working capital, energy costs and logistics constraints may have limited capacity to expand output in response to additional consumer demand.
Nevertheless, the policy settings alone do not establish that NERSI is crowding out private credit or forcing commercial overdraft rates to 34%. Such conclusions require actual lending-rate and credit-allocation data. The fiscal-monetary disconnect is therefore a question of coordination: household support can increase purchasing power, while the productive sector still needs affordable financing and reliable infrastructure to expand supply.
Consumer demand against supply-side constraints
The real economic value of a cash transfer depends on what beneficiaries can purchase and how effectively local suppliers can meet that demand. For low-income households, ₦50,000 can support spending on food, transport, healthcare and other essential needs. This expenditure may generate additional sales for market traders, retailers and service providers. Its wider effect, however, depends on beneficiary coverage, payment frequency, market supply and prevailing prices.
The Stanbic IBTC Nigeria PMI moderated to 55.7 in October 2026 from 56.4 in September, remaining above the 50-point expansion threshold for the ninth consecutive month. The survey reported continued private-sector growth, alongside increased fuel-related input and selling-price pressures. This provides a useful snapshot of business conditions, but does not establish that NERSI has increased retail demand or caused the reported price movements. Where local production and distribution respond adequately, additional household spending can support output and business turnover. Where supply is constrained, some of the increased purchasing power may instead be absorbed by higher prices. For corporate decision-makers, the distinction is between temporary demand support and sustained market expansion. The latter requires investment in production, logistics, energy reliability and working capital.
The unresolved fiscal commitment
NERSI’s financial implications cannot be assessed fully until the government clarifies its payment schedule. The Minister of Humanitarian Affairs and Poverty Reduction, Dr Bernard Doro, described the ₦50,000 support as monthly in an October 30 statement. Moniepoint’s published NERSI frequently asked questions, however, describe it as a one-off payment, with further payments subject to a separate government announcement. The central programme portal does not clearly reconcile the difference. This distinction changes the potential fiscal exposure. A one-time grant and a recurring monthly transfer create different expenditure requirements and funding commitments.
The central NERSI portal identifies five payment providers: ALAT by Wema Bank, MoMo PSB, NairaGram, OPay and Moniepoint. It provides for beneficiary consent, identity-linked wallets and USSD access on basic phones. The programme also allows withdrawals through banks and POS agents, where normal agent withdrawal fees may apply. The Ministry should publish the approved beneficiary target, funding envelope, actual disbursements and payment schedule. It should also provide transaction-performance information to demonstrate how reliably the funds reach intended recipients. Until those disclosures are available, neither the programme’s total fiscal exposure nor its aggregate economic effect can be established confidently.
Bold Lite strategic outlook: The test of economic value
NERSI should be evaluated through the relationship between public expenditure, monetary conditions and the response of the domestic economy. For fiscal authorities, the immediate requirement is a clear payment commitment supported by published funding and disbursement records. For monetary authorities, the task is to monitor liquidity and inflation through actual monetary aggregates and price data rather than assume a direct relationship between the grant and M2 growth. For businesses and investors, the important indicators are household purchasing power, input-cost movements, credit availability and domestic production capacity. These will determine whether the intervention supports a temporary consumption cycle or contributes to more durable commercial activity.
The ₦50,000 grant provides a direct household cushion. Its wider economic value, however, will depend on whether the fiscal commitment is sustainable, the delivery system is accountable and domestic supply can respond without excessive price adjustment.