
Nigeria’s manufacturing sector remained in expansion territory in October 2026, but weaker business-performance readings, unreliable electricity and elevated operating costs are exposing the financial burden of sustaining industrial production. Nigeria’s manufacturing business-performance index declined to 107.3 points in October 2026 from 108.4 points in September and 111.3 points in October 2025, according to the Nigerian Economic Summit Group’s (NESG) October Business Confidence Monitor (BCM). Although the reading remained above the 100-point expansion threshold, the decline indicates a moderation in reported business performance. The pressure was uneven across manufacturing subsectors. Textile, Apparel and Footwear fell sharply to 99.7 points from 127.5 points in September, moving into contraction territory. Cement also remained below the threshold at 94.5 points, while Food, Beverage and Tobacco was the only one of the three major subsectors to record improved performance and remain in expansion.
Manufacturers identified frequent power cuts, inadequate raw-material supplies, high rental costs, limited access to credit and infrastructure deficiencies among their major operating constraints. The wider cost-of-doing-business index stood at 45.2 points, while the prices index recorded 65.5 points. Both remained below the 100-point neutral threshold, indicating that a net majority of surveyed businesses continued to report elevated costs and selling prices. Financing conditions also weakened. The access-to-credit index fell to 122.7 points from 136.7 points in September, while the cash-flow index declined to 125.0 points from 140.4 points. Both remained in expansion territory, but the lower readings indicate that reported improvement in these conditions moderated.
The findings coincide with fresh electricity supply disruptions in early November. The Nigerian Independent System Operator identified inadequate gas supply and reduced water inflows into hydropower reservoirs among the constraints limiting generation. These developments reinforce the relevance of electricity reliability to manufacturers, although the NESG survey does not quantify the precise share of industrial costs attributable to power interruptions.
The industrial picture is therefore one of continued expansion under worsening operating conditions in selected areas. The central concern is whether manufacturers can preserve production margins, maintain working capital and finance capacity investment while managing unreliable electricity and high input costs.
Manufacturing Remains in Expansion, But Momentum Is Moderating
The October NESG monitor indicates that manufacturing business performance weakened for the second consecutive comparison against the previous year, although the sector remained above the survey’s expansion threshold.
|
Period |
Manufacturing Current Business Performance Index |
|
October 2025 |
111.3 |
|
September 2026 |
108.4 |
|
October 2026 |
107.3 |
The index declined by 1.1 points month-on-month and by 4.0 points compared with October 2025. This is a moderation in reported business performance, not evidence that manufacturing output contracted by 1.1%. The BCM is a survey-based indicator of business conditions. Its index should not be interpreted as a direct measurement of production volumes, factory utilization or manufacturing GDP. The distinction is reinforced by the Central Bank of Nigeria’s October Purchasing Managers’ Index. The CBN reported a composite PMI of 53.2 points, with the Industry PMI at 52.6 and the industrial output index at 53.5. These readings remained above the PMI expansion threshold of 50 points.
The two surveys are not directly interchangeable: NESG’s BCM measures reported business performance using a 100-point threshold, while the CBN’s PMI uses a 50-point threshold and a different survey methodology. Both, however, indicate continued expansion rather than a broad industrial contraction. The more important signal is that expansion is becoming harder to sustain. Manufacturers are operating in an environment where electricity, raw materials, financing and infrastructure continue to affect production economics.
Electricity Disruptions Are Raising the Cost of Industrial Operations
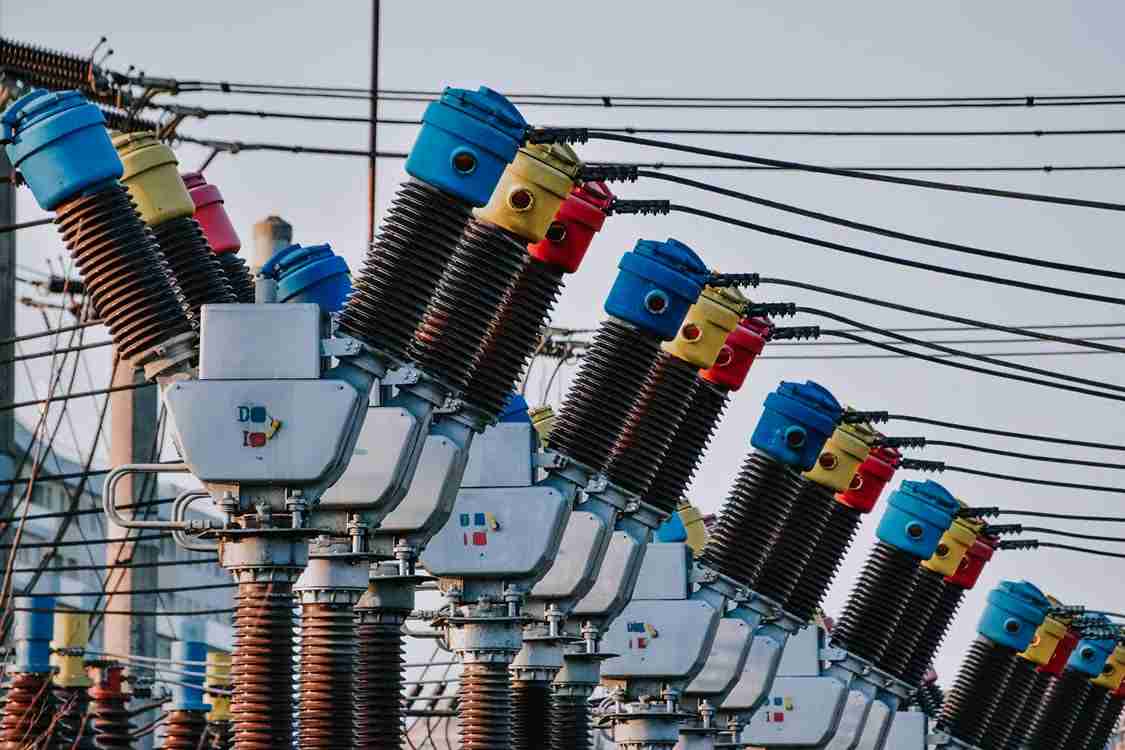
Manufacturing depends on predictable electricity for machinery, processing, refrigeration, automation and production scheduling. Interruptions can force factories to switch to alternative generation, adjust production shifts and absorb additional maintenance and fuel expenses. These costs extend beyond the purchase of diesel or gas. Unplanned interruptions can disrupt production cycles, reduce equipment utilization, delay orders and complicate inventory management. Where alternative power is more expensive than grid electricity, manufacturers face an additional operating burden. The October NESG monitor identified frequent power cuts and infrastructure deficiencies among the constraints reported by manufacturers. The issue remained visible in the wider electricity market during the first week of November.
On November 5, the 11 electricity distribution companies received a combined allocation of 2,926MW at the reported snapshot time. The Nigerian Independent System Operator attributed generation constraints to inadequate gas supply to thermal power stations and reduced water inflows into hydropower reservoirs. The Federal Government also acknowledged operational and maintenance challenges affecting supply in several states.
The allocation figure is a point-in-time distribution measure. It does not establish the volume ultimately delivered to customers, the duration of outages or the amount of electricity available to individual factories. Nevertheless, the developments demonstrate that electricity reliability remains a current operational concern. For manufacturers already dealing with elevated raw-material and financing costs, dependence on alternative generation can further weaken margins and reduce the funds available for maintenance and expansion.
Subsector Performance Shows Where Pressure Is Concentrated
The aggregate manufacturing index conceals substantial differences across industrial activities.
|
Subsector |
October 2026 index |
September 2026 index |
|
Textile, Apparel and Footwear |
99.7 |
127.5 |
|
Cement |
94.5 |
Not stated in the cited comparison |
Textile, Apparel and Footwear recorded a 27.8-point decline, moving below the 100-point threshold. Cement also remained in contraction territory at 94.5 points. Food, Beverage and Tobacco was the only one of the three largest manufacturing subsectors to record improved performance and remain in expansion during October. The wider subsector findings were also mixed. Chemical and Pharmaceutical Products, Plastic and Rubber Products, and Wood and Wood Products entered expansion territory. Pulp, Paper and Paper Products moved into contraction, while Non-Metallic Products remained below the threshold.
These differences matter because manufacturing subsectors do not face identical production economics. Energy intensity, raw-material availability, import dependence, customer demand and capital requirements vary considerably across industries. A single aggregate index can therefore conceal severe pressure in particular production chains even when the overall sector remains expansionary.
Credit And Cash Flow: The Working-Capital Constraint
Manufacturers need working capital to purchase inputs, hold inventory, pay suppliers, meet payroll and finance the interval between production and customer payment. When financing becomes more difficult or expensive, businesses may reduce inventory purchases, delay maintenance or postpone investment. The October BCM showed that the access-to-credit index declined to 122.7 points from 136.7 points in September. The cash-flow index fell to 125.0 points from 140.4 points.
Both readings remained above 100, meaning the survey continued to indicate expansionary conditions. Their decline shows that improvement moderated; it does not mean that credit access or cash flow contracted across the entire manufacturing sector. The pressure is nevertheless significant when considered alongside the cost indicators. Manufacturers must finance raw materials and production expenses while dealing with unreliable electricity and elevated operating costs. The challenge is particularly pronounced for smaller and medium-sized manufacturers with limited borrowing capacity, weaker collateral positions or insufficient cash reserves to absorb prolonged interruptions.
Without affordable working capital, even businesses with market demand may struggle to maintain production schedules and fulfil orders consistently.
High Operating Costs Continue to Weigh On Margins
The NESG cost-of-doing-business index stood at 45.2 points in October, up from 39.2 points in September. Its prices index increased to 65.5 points from 58.0 points. Both remained below the 100-point neutral threshold. The improvement indicates that the reported intensity of cost and price pressures eased relative to September, but a net majority of surveyed firms continued to report elevated costs and producer prices. This distinction is important: an improving index does not mean that input prices fell in absolute terms.
Manufacturers face a combination of energy expenditure, raw-material procurement, transport, rentals and financing costs. Their ability to absorb these expenses depends on pricing power, productivity and access to working capital. Businesses that cannot pass additional costs to customers may experience weaker margins. Those that increase selling prices may face resistance from customers whose purchasing power is already constrained. The result is a difficult commercial trade-off between protecting margins and preserving demand.
GDP and PMI Data Provide a Wider Industrial Picture
The latest available national accounts provide a useful baseline for assessing the survey findings. According to the National Bureau of Statistics’ Q2 2026 GDP data, manufacturing grew by 3.24% year-on-year, compared with 1.69% in Q2 2025. However, quarter-on-quarter growth moderated to 2.24% from 3.29% in Q1 2026.
The manufacturing sector contributed 7.72% to real GDP in Q2, down from 7.81% in the corresponding quarter of 2025. These figures show that manufacturing had returned to stronger year-on-year growth by the second quarter, but its contribution to the economy remained below the previous year’s level. They also predate the October BCM and should not be presented as October output figures. The CBN’s October PMI provides a more recent indicator of industrial direction. Its Industry PMI of 52.6 points and output index of 53.5 points indicate continued expansion under the CBN’s methodology.
Taken together, the GDP, PMI and NESG data describe an industry that is still growing but facing uneven momentum and persistent structural costs. The survey findings are particularly useful because they identify the operational constraints behind the moderation in reported business performance.
Business Expectations Remain Positive
Despite weaker current performance, the NESG Future Business Expectations Index increased to 130.8 points in October from 128.9 points in September. Manufacturing recorded an expectations index of 145.1 points. Trade registered 194.0 points, while Non-Manufacturing recorded 135.0 points. The NESG linked the improved outlook partly to anticipated festive-season demand and campaign-related spending ahead of the forthcoming general elections. The expectations index reflects business sentiment over the next one to three months. It is not a forecast of realized production, sales or investment. For manufacturers, stronger demand expectations will translate into improved performance only if businesses can secure raw materials, maintain electricity supply, finance inventory and deliver products at commercially viable costs.
Industrial Outlook: The Cost of Production Will Determine the Next Phase of Growth
Nigeria’s manufacturing sector has not entered broad contraction, but the October findings show that expansion is taking place under significant operating constraints.
Three areas will determine whether manufacturers can sustain growth.
Electricity reliability: More predictable grid supply and improvements in generation, transmission and distribution would reduce dependence on expensive backup power and make production planning more reliable. Industrial finance: Affordable working capital and longer-term investment funding are necessary to support raw-material procurement, equipment maintenance and capacity upgrades. Input and infrastructure efficiency: Reliable domestic raw-material supply, transport networks and industrial infrastructure would reduce avoidable costs and improve production continuity.
The next NESG business monitor and subsequent national accounts will help establish whether October’s moderation persists. For now, the evidence points to a manufacturing sector that remains expansionary but continues to face a high cost of sustaining production. The industrial policy question is therefore not simply how to increase factory output. It is how to reduce the structural costs that prevent manufacturers from converting available demand into sustainable production, stronger margins and productive investment.
References
- Central Bank of Nigeria (CBN) — October 2026 Purchasing Managers’ Index (PMI) Report.
Published November 2026. Confirms the October Industry PMI of 52.6 points, compared with 52.0 in September, and reports the industrial output and new-orders indices.
Read CBN October 2026 PMI Report - Nigerian Electricity Regulatory Commission (NERC) — Q2 2026 Operational and Commercial Performance Report.
Provides official electricity-sector data, including average grid generation, energy billing and collection, metering and distribution losses.
Read NERC Q2 2026 Report Highlights - National Bureau of Statistics (NBS) — Nigerian Gross Domestic Product Report, Q2 2026.
Official NBS dataset and report download. Use this source to verify manufacturing growth, sector contribution and quarterly performance before quoting those figures.
Access NBS Q2 2026 GDP Report - Nigerian Economic Summit Group (NESG) — Research and Publications Portal.
Official publication archive. The October 2026 Business Confidence Monitor was not visible in the archive when checked; the September edition was listed.
Access NESG Publications - NESG — Q2 2026 GDP Alert.
Provides NESG’s assessment of the Q2 economic performance and its interpretation of the manufacturing sector’s recovery and structural constraints. This is an institutional analysis of GDP data, not the original NBS statistical release.
Read NESG Q2 2026 GDP Alert