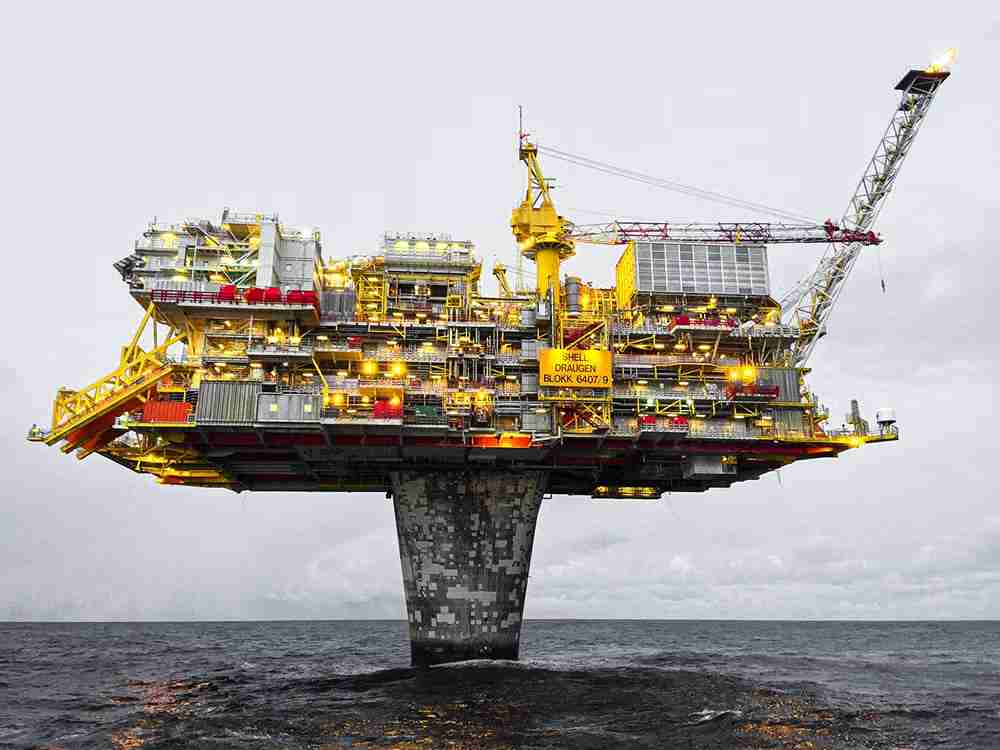

Expanding domestic refining capacity has changed the structure of the downstream petroleum market, but it has not removed the cost pressures facing manufacturers, distributors and other diesel-dependent businesses. The Dangote Petroleum Refinery has a stated nameplate capacity of 700,000 barrels per day. Yet the economic value of that capacity depends on reliable crude supply, refinery utilization, product yields, domestic allocation, wholesale pricing and the logistics required to move fuel from depots to industrial users. On November 12, 2026, the latest available national median for wholesale depot and gantry Automotive Gas Oil (AGO) stood at ₦1,698 per litre. This is a depot-market reference, not a delivered factory price. The actual cost to an industrial consumer can be higher after haulage, handling, financing and location-specific charges.
The central industrial question is therefore no longer simply whether Nigeria can refine more petroleum products domestically. It is whether the domestic supply chain can deliver competitively priced, reliably available fuel to productive businesses.
Refining Capacity Is Not the Same as Domestic Affordability
The Dangote refinery’s stated 700,000-barrel-per-day capacity represents a major expansion of Nigeria’s domestic refining infrastructure. However, nameplate capacity should not be confused with actual crude throughput, saleable product output or the volume delivered to Nigerian consumers. These are separate operating measures. A refinery may operate at a high utilisation rate while still exporting a substantial share of selected products. It may also require imported crude or other feedstock when domestic supply arrangements do not meet its requirements.
September 2026 data reported by the Nigerian Midstream and Downstream Petroleum Regulatory Authority showed that the refinery exported an average of 54.63 million litres per day of petrol, diesel and aviation fuel combined, compared with domestic supplies of 39.98 million litres per day across the same three product categories. The figures are significant, but their interpretation requires discipline. They do not show that diesel exports alone exceeded domestic diesel deliveries. Nor do they establish the refinery’s total output or the national balance between local production, imports, exports and consumption. They do, however, demonstrate why refinery capacity cannot be used as a standalone measure of domestic fuel affordability. The commercial outcome depends on how much product is available to local buyers, the price at which it is offered and the cost of moving it through the distribution network.
Diesel Pricing: The Depot Reference and Factory-Gate Cost
The latest available wholesale depot-price series placed Nigeria’s median AGO price at ₦1,698 per litre on November 12, 2026. The reading was unchanged from the immediately preceding observation and lower than the ₦1,765 recorded on November 7. This short-term movement indicates that depot prices had eased over the period. It does not establish a permanent reduction in industrial energy costs. The distinction between depot and delivered prices is essential. A manufacturer buying diesel must account for the depot quotation, transportation to its facility, loading and handling charges, payment terms, storage costs and any other applicable commercial charges. The final delivered price can therefore differ materially between factories, even when they purchase from the same depot.
For a business operating multiple plants across different locations, a single national depot benchmark is insufficient for procurement decisions. Management should compare suppliers using the actual delivered cost per litre, not simply the advertised gantry price. The same discipline applies when comparing domestic refining with imported supply. Local refining can reduce exposure to certain import-related costs, but domestic products remain influenced by crude acquisition costs, exchange-rate exposure, international product benchmarks, refinery economics and wholesale competition. Domestic production is an important supply-chain advantage. It is not an automatic guarantee of cheaper diesel.
Crude Supply: The Commercial Limit of The Naira-For-Crude Arrangement
The sustainability of domestic refining depends on access to feedstock at commercially viable prices and in sufficient quantities. The naira-for-crude arrangement was intended to strengthen the relationship between domestic crude production and local refining. Its effectiveness, however, depends on the consistency of cargo allocations, pricing terms, delivery schedules and the ability of refiners to meet their feedstock requirements through the arrangement. Reporting in July 2026 indicated that Dangote Refinery had raised concerns about inadequate domestic crude supply and the financial imbalance created when crude purchases were made in dollars while refined products were sold in naira. The refinery’s reported position was that its domestic allocations were below its stated monthly requirements.
In September, the refinery was reported to have secured at least 16 million barrels of Nigerian crude for October delivery through a combination of allocations and additional procurement. It also pursued other feedstock sources, including imported crude. These developments point to a mixed sourcing model rather than complete feedstock independence. For industrial users, the implication is direct. The cost of locally refined diesel remains exposed to the economics of crude procurement. If domestic supply is insufficient or commercially unattractive, refiners may need to source additional feedstock through alternative channels, potentially increasing their exposure to foreign exchange and international market movements.
The performance of the crude supply framework should therefore be assessed through actual monthly deliveries, refinery intake, procurement costs and payment arrangements—not policy announcements alone.
Manufacturing Energy Costs and Captive Power
Diesel remains an important operating input for manufacturers that rely on generators or other captive-power systems to supplement unreliable or insufficient grid supply. The Manufacturers Association of Nigeria has warned that power-related expenses, which previously accounted for about 40% of operating costs in the sector, had exceeded 50% following increases in energy costs. That statement should be understood as an industry-level warning attributed to MAN’s leadership, not as a uniform audited cost ratio for every factory. Energy exposure differs according to production technology, electricity consumption, generator efficiency, access to grid supply, product mix and operating hours. For energy-intensive manufacturers, however, the transmission mechanism is clear. Higher diesel prices increase the cost of captive electricity. Where businesses cannot pass those costs fully to customers, operating margins weaken. Where they do pass them on, production costs can feed into finished-goods prices and reduce consumer purchasing power.
The impact is particularly important for businesses with limited pricing power or substantial exposure to price-sensitive domestic demand. Manufacturers should therefore measure energy costs against production output rather than rely on broad sector averages. Useful indicators include diesel consumption per unit produced, electricity cost per unit, generator operating hours and the proportion of total energy expenditure attributable to captive generation.
Haulage Economics: The Cost Between Depot and Factory
The cost of industrial diesel does not end at the depot gate. Transportation charges vary according to distance, vehicle capacity, route conditions, security exposure, fuel consumption, loading arrangements, waiting time and the availability of return cargo. These variables make a single national haulage-inflation percentage unsuitable without a defined survey, route sample, measurement period and methodology.
The more useful approach is to examine the actual delivered cost on each procurement route. For manufacturers, the difference between depot and factory-gate prices should be recorded as a separate logistics cost. This allows procurement teams to identify whether cost increases originate from the product price, transportation, handling or supplier terms. The same principle applies to finished goods. Higher diesel costs can affect distribution fleets and third-party transport providers, creating a second channel through which energy-price movements reach manufacturers and consumers. The extent of that pass-through must be established using actual freight invoices and route-level data. It should not be assumed to be identical across sectors or locations.
Working Capital and Industrial Energy Procurement
Fuel procurement also has a financing dimension. Manufacturers that maintain diesel inventories commit cash to an operating input before the fuel is converted into production output and, ultimately, sales revenue. When prices rise, the amount of working capital required to maintain the same physical inventory increases. The Central Bank of Nigeria’s September 2026 monetary policy decision set the Monetary Policy Rate at 23% and retained the Cash Reserve Ratio for deposit money banks at 45%.
These policy settings are relevant to the broader cost of credit and liquidity available to businesses. They should not, however, be treated as a direct formula for diesel pricing. The commercial exposure is best measured at company level. Businesses with long procurement cycles, weak cash conversion and high fuel consumption may face greater financing pressure than competitors able to replenish stock more frequently or negotiate better supplier terms. A disciplined procurement strategy should link inventory decisions to consumption patterns, supplier reliability, delivery lead times and available working capital. A fixed diesel-stock duration should not be imposed across manufacturers with different operating requirements.
C-Suite Industrial Energy Scorecard
Industrial management teams should track the following indicators consistently:
| Performance indicator | Measurement | Management purpose |
| Delivered diesel cost | Total delivered invoice cost ÷ litres received | Establish the true factory-gate price |
| Energy cost per unit | Total energy expenditure ÷ production units | Measure energy intensity |
| Diesel consumption intensity | Litres consumed ÷ production units | Track generator and process efficiency |
| Fuel inventory days | Usable stock ÷ average daily consumption | Monitor supply continuity and cash commitment |
| Logistics cost per litre | Total fuel transportation and handling costs ÷ litres delivered | Isolate distribution inefficiency |
| Captive-power dependence | Captive electricity ÷ total electricity consumed | Measure exposure to diesel-based generation |
| Energy cost variance | Actual energy expenditure against budget | Identify price and consumption deviations |
These indicators should be reviewed monthly and compared across plants, suppliers and procurement routes. Where possible, management should separate price variance from consumption variance so that operational inefficiency is not mistaken for a market-price increase.
Strategic Outlook: The Next Competitive Advantage Is Delivery
Nigeria’s domestic refining expansion has created a stronger foundation for petroleum-product supply. The next phase of its industrial value will depend on whether that capacity translates into reliable domestic availability, transparent pricing and lower delivered costs.
First, crude supply arrangements must become predictable enough to support efficient refinery operations. Domestic refiners cannot deliver stable commercial outcomes if feedstock procurement remains uncertain or excessively exposed to foreign exchange disruptions. Second, wholesale competition must transmit supply improvements into prices paid by local businesses. Refinery output and export earnings are important commercial indicators, but they do not independently establish affordability for domestic industrial users. Third, distribution infrastructure must reduce the cost and uncertainty between depots and factories. Better procurement contracts, route planning, storage management and supplier competition can help manufacturers control the logistics component of their energy bills.
The policy and commercial debate should move beyond installed refining capacity. The relevant measures are actual crude intake, product output by category, domestic deliveries, wholesale price movements and the final delivered cost to industrial consumers.
For manufacturers, the immediate priority is to improve energy productivity and procurement visibility. For refiners and regulators, the test is whether domestic capacity can support a competitive, dependable market without creating new supply bottlenecks. “Nigeria’s refining transition will deliver its full industrial value when domestic production is matched by dependable feedstock, competitive wholesale pricing and efficient delivery to the factory gate.”